

What's Happening?
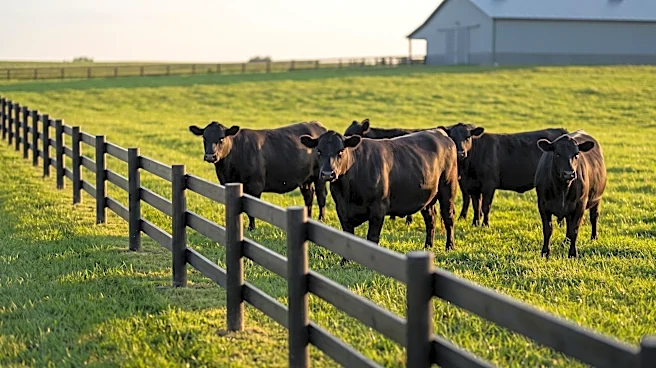
Chicago Mercantile Exchange (CME) cattle futures experienced a decline on Friday, with November feeder cattle settling 5.200 cents lower at 331.150 cents per pound and December live cattle finishing down 1.700 cents at 221.475 cents per pound. This drop
occurred despite weakness in the U.S. grains markets, which typically might offer some support to livestock. Cash trade for live cattle softened, with prices in northern markets at $220 per hundredweight (cwt), a $2 decrease from the previous week. However, southern cash markets saw live cattle trading at $225 per cwt, prompting some operators to transport animals to Oklahoma and Texas for better prices. Wholesale beef prices were mixed, with Choice cuts falling $2.43 to $374.36 per cwt, while Select cuts rose $0.47 to $353.36 per cwt, according to the USDA. Pork wholesale prices, including the carcass cutout and bellies, saw increases.
Why It's Important?
The decline in cattle futures and softening cash trade indicate a challenging period for the U.S. livestock industry. Lower prices for live cattle directly impact ranchers and feedlot operators, potentially reducing their profitability and influencing future breeding and feeding decisions. The disparity between northern and southern cash markets highlights regional supply and demand dynamics, leading to increased transportation costs for some producers seeking higher prices. Mixed wholesale beef prices suggest fluctuating consumer demand or processing bottlenecks, affecting meatpackers' margins. Meatpackers' profits per head of cattle significantly decreased, from $126.45 on Thursday to $69.35 on Friday, signaling tighter margins in the processing sector. This situation could lead to adjustments in slaughtering schedules and procurement strategies, ultimately influencing the availability and pricing of beef for consumers.
What's Next?
Traders are actively seeking seasonal support in the cattle markets, with some hoping for a boost from the corn market, which has been under pressure. The recovery of slaughtering operations following recent disruptions, with an estimated 100,000 cattle slaughtered on Friday, up from 87,000 a week prior, suggests an effort to stabilize processing capacity. However, the continued pressure on meatpacker profits may lead to further adjustments in their operations or pricing strategies. The mixed signals from wholesale beef prices indicate ongoing market volatility. Stakeholders in the cattle industry will closely monitor grain prices, consumer demand for beef, and the efficiency of meatpacking operations to anticipate future market movements and make informed decisions regarding production and sales.
Beyond the Headlines
The current market dynamics in the cattle industry reflect broader economic and logistical challenges. The impact of an immigration crackdown on meatpacking plant workers, mentioned as a factor in previous disruptions, underscores the vulnerability of the agricultural supply chain to labor issues. The fluctuating profitability for meatpackers, despite increased slaughter rates, points to the complex interplay of input costs, wholesale prices, and operational efficiencies. This situation could accelerate the adoption of automation in meat processing or lead to shifts in regional production to optimize costs. Furthermore, the differing prices in northern and southern cash markets highlight the importance of regional market analysis for producers and the potential for increased competition or consolidation within the industry as businesses adapt to these pressures. The overall trend suggests a need for resilience and adaptability within the U.S. livestock sector.