
The Classic Savings Problem
Fixed Deposits (FDs) are a go-to savings tool in India for a reason: they are safe, predictable, and easy to understand. You invest a lump sum for a fixed period (tenure) at a guaranteed interest rate. The problem? Your money is locked in. If you put
a large sum into a single five-year FD, you cannot touch it without facing a penalty for premature withdrawal. This creates a liquidity crunch, forcing you to choose between earning good returns and having access to your own money.
What is FD Laddering?
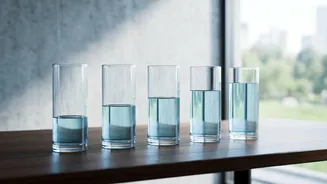
FD laddering is a strategy where you split a large investment into several smaller FDs with different maturity dates. Instead of one big FD, you create a "ladder" where each FD is a "rung". For example, instead of investing ₹1,00,000 in a single 5-year FD, you could split it into five FDs of ₹20,000 each. You would invest them to mature in one, two, three, four, and five years respectively. This simple diversification of tenures is the key to unlocking control over your cash flow.
Building Your First FD Ladder
Creating your own FD ladder is straightforward. First, decide on your total investment amount and the number of FDs (rungs) you want in your ladder; three to five is a common starting point. Next, divide your total amount equally among the FDs. Then, stagger the tenures. If you're creating a five-rung ladder, you would open FDs that mature in one year, two years, three years, four years, and five years. As each FD matures, you have a decision to make: you can either use the money for a planned expense or reinvest it into a new, long-term FD, keeping the ladder structure going.
The Power of Predictable Liquidity
The primary benefit of this strategy is enhanced liquidity. Because the deposits mature at different times, a portion of your investment becomes available to you at regular intervals—every year, in our example. This creates a predictable cash flow. If an unexpected expense arises, you know that one of your FDs is maturing soon, reducing the need to break a larger deposit and incur penalties. This gives you the flexibility to meet financial requirements, whether it's for travel, education fees, or an emergency, without disrupting your entire savings plan.
Averaging Interest Rates for Better Returns
FD laddering also helps you manage interest rate risk. Interest rates fluctuate over time. If you lock all your money in a single long-term FD, you might miss out if rates go up. With a ladder, only a part of your investment is renewed at a time. If rates rise, the next maturing FD can be reinvested at the new, higher rate. If rates fall, the other FDs continue to earn at their previously locked-in higher rates until they mature. This process of interest rate averaging can lead to better overall returns over time compared to a single FD.
Is It the Perfect Strategy?
While powerful, FD laddering is not a magic bullet for the highest possible returns. The returns from FDs may not always beat inflation, and other investment options like equities offer higher growth potential. Furthermore, managing multiple FDs requires a bit more organization than a single one. You'll need to keep track of different maturity dates and renewal instructions. However, for a young beginner focused on capital protection, predictable cash flow, and disciplined saving, the benefits of control and liquidity often outweigh these minor complexities.