





The Big UPI Change: Merchant Fees Explained
Starting October 15, 2026, the way some UPI payments are charged is changing, but here's the most important part for you as a user: sending money to friends or family remains completely free. The new rule introduces a 'Merchant Discount Rate' (MDR), which
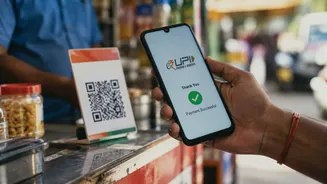
is a fee that certain merchants will pay when they receive a UPI payment over ₹2,000. This fee is 0.4% of the transaction value, and it is paid by the business, not you. In short, if you are buying something for more than ₹2,000, the merchant might incur a small charge. However, they are strictly prohibited from passing this cost on to you as a 'UPI fee'. For the vast majority of your daily transactions—like paying for chai, groceries, or splitting a bill—nothing changes. Over 96% of merchant payments will not be affected.
Are All Merchants Included?
No, and this is a key detail. The new MDR framework is designed to help sustain the payments ecosystem without burdening small businesses or essential services. Everyday small merchants are exempt from these charges. Furthermore, specific essential sectors like railways, fuel, telecom, and insurance have a different, lower fee structure, which will also be borne by the merchant. Transactions for investments, like mutual funds or stockbroking, also have a much lower fee. The bottom line is that while there is a lot of discussion about UPI charges, these are backend changes for businesses. Your user experience of scanning a QR code and paying remains seamless and, for all practical purposes, free.
Savings Rule 1: ATM Withdrawal Limits
If you're an SBI customer, there's a notable change for salary package accounts starting October 1, 2026. The number of free transactions you can make at other banks' ATMs is being reduced from ten per month to five. This limit covers both financial transactions (like withdrawing cash) and non-financial ones (like checking your balance). For those with a Basic Savings Bank Deposit (BSBD) account with SBI, the rule of four free cash withdrawals per month continues. After the free limit is used, each additional withdrawal will cost ₹15 plus GST. It's a clear signal from banks encouraging more digital transactions, which continue to be unlimited and free.
Savings Rule 2: New Norms for Fixed Deposits
The Reserve Bank of India (RBI) has introduced new rules for how banks handle bulk fixed deposits (generally large deposits of ₹3 crore or more) from October 1. Banks now have to be more transparent, announcing their interest rates for these large deposits in advance each day. While this directly affects high-net-worth individuals and companies, it signals a broader push for transparency in the savings landscape. For young retail investors with smaller FDs, this change doesn't directly alter your interest rates. However, it contributes to a more predictable and open banking environment, which is a long-term positive for all savers.
Other Financial Updates to Note
A couple of other changes are also effective this month. For those investing in the National Pension System (NPS), the fee structure for accounts opened via a Point of Presence (PoP) has been revised from October 1. This includes a one-time onboarding fee. Additionally, completing your KYC has become mandatory for receiving LPG subsidies, another step in linking government benefits directly and transparently. These changes, while seemingly small, are part of a larger trend of formalising India's financial systems, improving tracking, and ensuring benefits reach the right people.