



The Core Conflict: Certainty vs. Potential
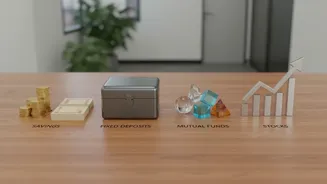
At its heart, the choice between a Fixed Deposit (FD) and a market investment like stocks or mutual funds is a choice between a guarantee and a possibility. An FD, offered by banks, is a straightforward promise: you lock in your money for a fixed period
and get a pre-determined interest rate. Your principal is protected, and you know exactly how much you'll earn. Market investments, on the other hand, offer no such guarantees. When you buy a stock or a mutual fund unit, you are buying a small piece of a business whose value can rise or fall based on company performance, economic conditions, and investor sentiment. The potential for high returns is significant, but so is the risk of loss.
Understanding Risk and Return
Fixed Deposits are considered one of the safest investment options because they are not subject to market fluctuations. They are ideal for risk-averse individuals or for short-term goals where capital preservation is paramount. The returns are modest but assured. The stock market is the opposite. It is inherently volatile. Share prices can fluctuate dramatically, meaning you could lose some or all of your invested capital. However, this risk is compensated by the potential for much higher returns over the long term. Historically, equities have shown the potential to deliver returns that significantly outpace FDs.
The Battle Against Inflation
A crucial, often overlooked, factor is inflation—the rate at which the cost of living increases. This is where FDs often struggle. If your FD offers a 6% return but inflation is at 5.5%, your real return (your gain in purchasing power) is only 0.5%. After taxes are deducted from your interest income, your real return can even become negative, meaning your money is losing purchasing power despite growing in absolute terms. Equity investments, while volatile, have historically delivered long-term returns that comfortably beat inflation, helping your wealth grow in real terms.
Liquidity: How Easily Can You Access Your Money?
Liquidity refers to how quickly you can convert your investment back into cash. Here, market investments often have an edge. Open-ended mutual funds and publicly traded stocks can usually be sold on any business day. Fixed Deposits have a lock-in period. While you can break an FD prematurely, banks typically charge a penalty, which reduces your overall returns. This makes FDs less suitable for funds you might need in an emergency.
How Your Gains Are Taxed
The tax treatment for FDs and market investments is vastly different. Interest earned from an FD is added to your total income and taxed according to your income tax slab. For someone in the highest tax bracket, this can significantly reduce the net return. Market investments have a more complex but often more favourable tax structure. Gains from selling equity shares or equity mutual funds are categorised as Short-Term Capital Gains (STCG) if held for less than 12 months, or Long-Term Capital Gains (LTCG) if held for longer. As of 2026, LTCG on equity above a certain threshold is taxed at a flat rate that is often lower than the highest income tax slabs, making it more tax-efficient for long-term wealth creation.