


The Unseen Force of Compound Growth
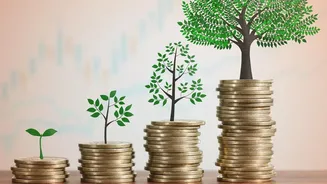
Albert Einstein reportedly called compound interest the 'eighth wonder of the world'. It's the process where you earn returns not just on your initial investment, but also on the accumulated interest from previous periods. Think of it as a snowball rolling
downhill. It starts small, but as it gathers more snow, it grows bigger and faster. Your investment works the same way. The first few years of growth might seem modest. But over decades, the effect becomes profound, leading to exponential growth. This is why time is the single most important ingredient in any successful long-term investment strategy. The longer your money stays invested and untouched, the more powerful the compounding effect becomes, doing the heavy lifting for your future financial security.
The Immediate Pain: Taxes and Penalties
When you pull money from a retirement fund like the Employee Provident Fund (EPF) or National Pension System (NPS) before the stipulated time, the first hit you feel is immediate. For instance, withdrawing from your EPF before completing five years of continuous service makes the amount taxable. If the amount is over ₹50,000, Tax Deducted at Source (TDS) will apply. Similarly, the NPS has strict rules. You can only make partial withdrawals for specific reasons after being in the system for at least three years, and even then, it's capped at 25% of your own contributions, not the total corpus. These rules are not there to be difficult; they are designed to protect your savings from you. They act as a strong deterrent against treating your retirement fund like a regular savings account.
The Real Cost: Lost Future Growth
The taxes and penalties are just the tip of the iceberg. The far greater, and often invisible, cost is the lost opportunity for future compound growth. When you withdraw funds, you aren't just taking out that principal amount; you are stealing from your future self. You are removing a chunk of the 'snowball' and permanently shrinking its future potential. A withdrawal of ₹1 lakh today doesn't just cost you ₹1 lakh. It costs you the ₹5 lakhs or ₹10 lakhs that the amount could have grown into over the next 20 or 30 years. This opportunity cost is massive. Withdrawing during a market downturn is even worse, as you lock in losses, and your remaining capital has to work much harder just to recover to its previous level.
Are There Ever Good Reasons to Withdraw?
Of course, serious emergencies happen. Indian retirement schemes like the EPF and NPS allow for partial withdrawals for specific, critical life events like medical emergencies, children's higher education or marriage, or buying a home. These are considered legitimate reasons because they address significant life needs. However, even in these situations, it's crucial to exhaust all other options first. Could you take a loan against property or gold? Do you have an emergency fund you can dip into? Exploring alternatives like a Systematic Withdrawal Plan (SWP) from a mutual fund for planned expenses or taking a loan against your investments can sometimes be a less damaging option than breaking into your core retirement corpus. The goal should always be to leave your long-term compounding engine running with as little interruption as possible.