



First, What Exactly Is UPI?
Imagine a world where you could pay any shop or person directly from your bank account in seconds, using any payment app on your phone, with almost no fees. That’s the core idea behind India's Unified Payments Interface, or UPI. It's not a single app like
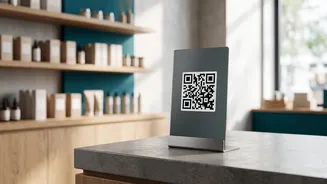
Venmo or Cash App, but rather the powerful, open network that runs underneath them. Developed by the National Payments Corporation of India, UPI created a single, interoperable system that connects all major banks. This means a customer using Google Pay can seamlessly send money to a merchant using a completely different bank's app. The transaction is instant, secure, and happens 24/7. For businesses, the barrier to entry is incredibly low. Instead of needing an expensive point-of-sale terminal, a small shop can start accepting digital payments with nothing more than a bank account and a printed QR code.
The Real Game-Changer: Slashing Fees
The single biggest impact of a system like UPI is its effect on the bottom line. In the U.S., every time a customer swipes a credit card, the merchant loses around 1.5% to 2.5% of the sale to what’s called a Merchant Discount Rate (MDR). On a $100 sale, that’s up to $2.50 gone before the money even hits your account. For a small coffee shop or boutique running on thin margins, those fees add up to thousands of dollars a year. The UPI model flips this script entirely. For years, UPI transactions in India were completely free for merchants, a policy that supercharged its adoption. More recently, a very small fee of 0.4% has been introduced for some larger transactions, but it remains dramatically cheaper than card payments. A transaction that might cost a U.S. merchant $2.00 could cost a fraction of that on a UPI-like system, allowing them to keep more of their hard-earned revenue.
Instant Cash and Better Security
Beyond the lower costs, two other benefits have made UPI a favorite among small businesses. The first is instant settlement. Unlike credit card payments, which can take two or three business days to batch and transfer, UPI payments move from the customer's bank to the merchant's bank in real time. This has a massive impact on cash flow, giving small business owners immediate access to their funds instead of waiting for them to clear. The second advantage is security. With UPI, the customer authorizes every payment from within their own secure banking app using a PIN. The merchant never sees or stores the customer's sensitive bank account or card details. This significantly reduces the risk of data breaches and simplifies the compliance burden for small shops, who no longer need to worry about protecting troves of financial data.
So, When Is It Coming to America?
Here's the reality check: while UPI provides a powerful model, you won’t be seeing it at your local farmers market just yet. The U.S. payments landscape is fundamentally different from India's when UPI was launched. America has a deeply entrenched, highly profitable credit card ecosystem dominated by giants like Visa and Mastercard. These companies, and the banks that issue their cards, have little incentive to support a low-cost alternative that would disrupt their revenue from transaction fees. Furthermore, UPI's explosive growth in India was driven by a coordinated push from the government and central bank to encourage digital payments, something that isn't happening in the same way here. While the U.S. has its own real-time payments network, FedNow, it has not been designed to function as the kind of low-cost, merchant-focused solution that made UPI a phenomenon.