Equity: The Engine for Growth
Equity is the part of your portfolio designed for growth. When you buy stocks or equity mutual funds, you are buying a small piece of a company. As the company grows its business and profits, the value of your ownership stake can increase significantly
over time. This potential for capital appreciation is why equity is considered the primary engine for wealth creation. Historically, equities have delivered returns that outpace inflation over the long term, helping your money grow in real terms. However, this growth potential comes with higher risk and volatility. Share prices can fluctuate significantly in the short term due to market sentiment, economic news, or company-specific events. For this reason, equity is best suited for long-term goals, like retirement or a child’s future education, giving your investment enough time to recover from market downturns and compound effectively.
Debt: The Anchor of Stability
If equity is the aggressive run-scorer, debt is the reliable defender holding the other end. Debt instruments—such as Fixed Deposits (FDs), the Public Provident Fund (PPF), and various government or corporate bonds—are essentially loans you make to an entity in exchange for regular interest payments. Their main role is to provide stability and capital preservation to your portfolio. Unlike equities, the returns from debt are more predictable and far less volatile. This makes them ideal for investors with a lower risk appetite or for goals that are just a few years away. When equity markets are in turmoil, the debt portion of a portfolio provides a crucial cushion, preventing steep losses and generating a steady, if modest, income stream. While returns are typically lower than equity, the stability they offer is not just a defensive measure; it is a critical component for balancing risk across your entire investment strategy.
Gold: The Portfolio's All-Rounder
Gold plays a unique and often misunderstood role. It's not just a traditional asset or a safe-haven purchase during festivals; it’s a powerful diversification tool. The key feature of gold is its historically low correlation with other financial assets like stocks and bonds. This means gold’s price often moves independently, sometimes even rising when equity markets are falling, such as during times of economic crisis or high inflation. For Indian investors, gold also acts as a hedge against currency depreciation. Since gold is priced globally in US dollars, a weaker rupee can lead to higher gold prices in India, protecting the purchasing power of your investment. While not expected to be the primary growth driver, a strategic allocation to gold (often 5-15%) can reduce overall portfolio volatility and provide a safety net during periods of widespread market uncertainty, making your financial journey smoother.
Building Your Winning Team
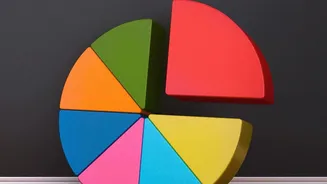
The real magic happens when you combine these three distinct asset classes. Relying solely on equity exposes you to severe volatility. Sticking only to debt may cause your wealth to fall behind inflation. Investing only in gold means missing out on the growth of the broader economy. Asset allocation—the process of deciding what percentage of your money goes into each bucket—is the single most important decision you will make. A common starting point for a balanced approach might be a mix like 60% equity, 30% debt, and 10% gold. Young investors with a long time horizon might lean more heavily into equities, while those approaching retirement may increase their allocation to debt for capital preservation. The goal is not to find the single “best” asset but to create a blended portfolio where the different components work together, balancing each other out through various market cycles to help you reach your financial goals steadily and surely.