



Beyond the Paycheck: What Is Net Worth?
Many people focus on their monthly income and expenses, but this only tells part of the story. Your net worth provides a complete snapshot of your financial health. The calculation is simple: it's the total value of everything you own (your assets) minus
the total of everything you owe (your liabilities). Assets include cash in the bank, investments, the value of your vehicle, and property. Liabilities include credit card debt, student loans, and mortgages. The resulting number, whether positive or negative, is your net worth. It isn't a measure of your self-worth, but a starting point. The real power comes from watching how this number changes over time.
The Psychology of Tracking: What Gets Measured, Gets Managed
The magic of tracking net worth isn't in the spreadsheet or the app; it's in your head. Research on habit formation shows that the simple act of observing your own behaviour is often enough to change it. Just as keeping a food diary can lead to healthier eating, tracking your finances promotes healthier financial habits. When you see your net worth number each month, your financial decisions become more tangible. That forgotten subscription or daily coffee run is no longer just a small expense; it's a direct impact on your wealth-building goal. This awareness naturally encourages better habits, such as saving more consistently, paying down debt more aggressively, and spending more deliberately. It turns the abstract goal of "building wealth" into a concrete, visible trend line, providing motivation and a sense of control.
The Engine of Growth: How Compounding Ignites Savings
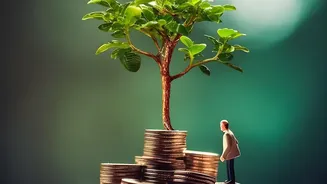
Consistent tracking helps you save more, and those savings are the fuel for the powerful engine of compound interest. Compounding is the process where you earn returns not just on your original investment, but also on the accumulated interest or gains from previous periods. It creates a snowball effect that can turn small, regular contributions into a massive sum over decades. For example, the difference between starting to invest at age 25 versus 35 can be enormous, even with the same monthly contribution, because the first decade gives your money much more time to grow on its own. After a few years, you may notice that your investments are growing by more than what you're contributing each month—that's the moment the magic of compounding becomes truly visible.
From Small Beginnings to Significant Wealth
Let's connect the dots. You start tracking your net worth. This new awareness prompts you to find an extra bit of savings each month—say, the equivalent of a few cancelled subscriptions or fewer takeaway meals. You invest this small, consistent amount early in your career. At first, the growth is slow. But as the years pass, the power of compounding takes over. That small, disciplined saving habit, reinforced by the positive feedback of seeing your net worth grow, creates a virtuous cycle. The behaviour (tracking and saving) feeds the mathematical engine (compounding), and the result is wealth that grows exponentially over time. Studies have shown that people with a written financial plan have a significantly higher net worth, and tracking is the foundation of any good plan.
How to Start Tracking Your Net Worth Today
Getting started is simpler than you might think. First, make a list of your assets and their current value. Next, list all your liabilities and their outstanding balances. Subtract your total liabilities from your total assets to get your starting net worth. You can use a simple spreadsheet, a notebook, or a dedicated financial app. The tool doesn't matter as much as the consistency. Plan to update it once a month. This frequency is enough to see progress and make adjustments without getting stressed by daily market fluctuations. Don't be discouraged if your number is low or even negative at the start; the most important thing is the direction it moves in the months and years to come.