
What is an FD Ladder?
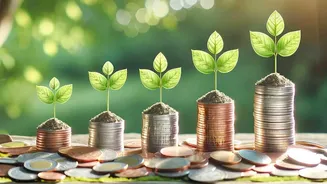
Imagine a ladder. Each rung represents a Fixed Deposit. Instead of parking a large sum of money into a single FD for a long period, you split it into smaller amounts and invest them in multiple FDs with different maturity dates. For example, instead of putting
₹5 lakh in one five-year FD, you could create five FDs of ₹1 lakh each, with them set to mature in one, two, three, four, and five years, respectively. This creates a 'ladder' of investments, with one FD maturing every year, giving you a predictable stream of cash.
The Triple Advantage: Liquidity, Returns, and Discipline
The primary benefit of this strategy is enhanced liquidity. Since an FD matures at regular intervals, you have access to a portion of your money without having to break a larger deposit and pay a penalty. Secondly, it helps you average out interest rates. If you lock all your money in a single FD, you risk doing so at a time when rates are low. Laddering allows you to reinvest maturing funds at potentially higher prevailing rates, optimising your overall returns. Lastly, it instils financial discipline, encouraging long-term planning and discouraging impulsive withdrawals.
Step 1: Assess and Allocate Your Corpus
First, decide how much money you want to dedicate to your FD ladder. This should be a lump sum you don't need for immediate daily expenses, such as a bonus, inheritance, or accumulated savings. Be realistic about the amount. This strategy is about making your stable, long-term savings work more efficiently. It's not a substitute for an emergency fund that you might need to access at a moment's notice, though a well-structured ladder can certainly supplement it.
Step 2: Divide Your Investment into 'Rungs'
Once you have your total amount, divide it into equal parts. Each part will become a 'rung' on your ladder. Most financial planners suggest starting with three to five rungs for a manageable and effective ladder. For instance, if your corpus is ₹10 lakh and you decide on a five-rung ladder, you will create five separate FDs of ₹2 lakh each. Keeping the amounts equal makes the ladder balanced and easy to track.
Step 3: Stagger the Maturity Dates
This is the most crucial step. You need to open each FD with a different tenure. Using our ₹10 lakh example, you would invest the five chunks of ₹2 lakh into FDs with tenures of one year, two years, three years, four years, and five years. This ensures that starting from the end of the first year, you have one FD maturing annually. Currently, FD rates in India can range from around 3% to over 8%, with longer tenures generally offering higher rates.
Step 4: Reinvest and Climb Higher
The real power of the FD ladder comes from reinvestment. When your first FD (the one-year deposit) matures, you take the principal and the interest earned and reinvest it into a new FD for the longest tenure in your ladder—in this case, five years. When the two-year FD matures the following year, you do the same. Over time, all your FDs will become long-tenure deposits earning higher interest, but you will still have one maturing every single year, providing that vital liquidity.
Things to Keep in Mind
While laddering helps avoid premature withdrawals, be aware of the penalties, which typically range from 0.5% to 1% of the interest rate if you absolutely must break a deposit. Also, remember that the interest earned on FDs is taxable according to your income tax slab. Laddering can sometimes help manage your tax liability by spreading interest income across different financial years, which can be useful for avoiding automatic TDS deductions.