
Step 1: Understand the Core Difference
Before you move a single rupee, it’s crucial to understand the distinction between saving and investing. Saving is setting aside money for short-term goals and emergencies, like a vacation or an unexpected medical bill. It’s typically low-risk, meaning
your money is safe, but it also offers very low returns, often not even enough to beat inflation. Investing, on the other hand, is putting your money into assets like stocks or mutual funds with the expectation that it will grow over the long term. It involves taking on more risk for the potential of much higher returns. Savings provide security; investments build wealth.
Step 2: Build Your Financial Safety Net
Never invest money you might need in a crisis. Before you even think about investing, you must build an emergency fund. This is a pool of money, kept in a highly accessible savings account, to cover three to six months of essential living expenses. This fund is your shield against life’s surprises, like a sudden job loss or a car repair. Having this safety net prevents you from being forced to sell your investments at the wrong time to cover an emergency, which could derail your long-term goals. Consider this step non-negotiable.
Step 3: Define Your Financial Goals
Why are you investing? Without clear goals, your financial plan will lack direction. Your objectives determine your entire strategy, from your investment choices to your timeline. Are you saving for a down payment on a house in five years? Your child’s education in 15 years? Or your retirement in 30 years? Short-term goals require less risky investments, while long-term goals allow you to take on more risk for higher growth potential. Writing down your goals makes them tangible and keeps you motivated during market ups and downs.
Step 4: Assess Your Comfort with Risk
Your risk tolerance is your emotional and financial ability to handle fluctuations in the value of your investments. It’s influenced by factors like your age, income, and personality. Are you someone who would panic and sell everything during a market dip, or can you stomach the volatility for potential long-term rewards? A younger investor with a long time horizon can generally afford to take more risks than someone nearing retirement. Understanding your comfort level is key to choosing investments that you can stick with for the long haul.
Step 5: Explore Your Investment Options
For beginners in India, there is a wide range of investment options. You don't need to be an expert to start. Mutual Funds are often a great starting point, as they are professionally managed and offer instant diversification. A Systematic Investment Plan (SIP) allows you to invest a fixed amount regularly, making it disciplined and affordable. Other options include the Public Provident Fund (PPF) for long-term, tax-advantaged savings and even direct stocks (equity) for those willing to do more research. The key is to start with products you understand.
Step 6: Don't Put All Your Eggs in One Basket
Diversification is one of the most important principles in investing. It simply means spreading your money across different types of assets (like stocks and bonds), industries, and geographical regions. The idea is that when one part of your portfolio is performing poorly, another part may be doing well, which helps to smooth out your returns and reduce overall risk. Mutual funds and Exchange-Traded Funds (ETFs) are excellent tools for achieving diversification without having to buy dozens of individual stocks yourself.
Step 7: Automate and Be Patient
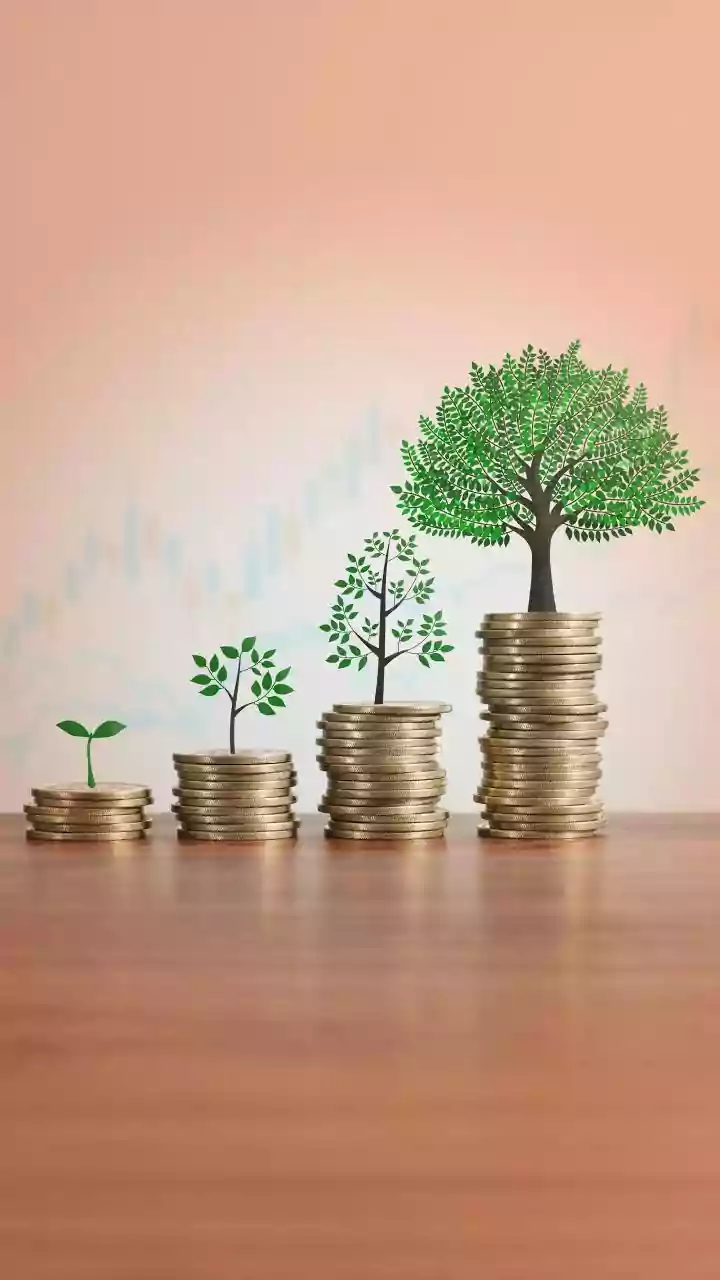
The secret to building wealth isn't timing the market; it's time in the market. One of the most effective strategies is to automate your investments through a monthly SIP. This enforces discipline and removes emotion from your decisions. By investing a consistent amount regularly, you also benefit from a strategy called rupee cost averaging. Most importantly, be patient. Wealth isn't built overnight. The real magic happens through the power of compounding, where your returns start earning their own returns. The longer you stay invested, the more powerful this effect becomes.