


Create a Dedicated Travel Fund
The first and crucial step is to separate your travel savings from your everyday finances. Open a new, dedicated savings account and label it 'Travel Fund'. This simple act of compartmentalization creates a psychological barrier, making you less likely
to dip into your vacation money for daily expenses. It also makes tracking your progress exciting and tangible. Seeing the balance grow serves as a powerful motivator to stay disciplined and keep your travel goals in sight. Many banks in India offer high-yield savings accounts that can help your money grow a little faster while you plan.
Make Your Savings Automatic
Don't rely on willpower alone. The moment your bonus or freelance payment hits your primary account, manually transfer a significant portion to your dedicated travel fund. Better yet, set up automatic transfers. You can schedule a recurring transfer to align with your regular paydays or create a rule for yourself to immediately move a percentage of any freelance income. This 'pay yourself first' strategy ensures that saving for travel becomes a consistent habit, not an afterthought. By automating, you move the money before you're tempted to spend it.
Define Your Travel Goals
A vague goal of 'travel more' is hard to save for. Get specific. Where do you want to go? For how long? What kind of experience do you want? Research the approximate costs of flights, accommodation, food, and activities for your dream destination. This transforms your abstract dream into a concrete financial target. Knowing you need ₹75,000 for a week in Thailand is a much clearer goal than just 'saving for a trip'. This clarity will help you determine how much you need to set aside from each bonus or freelance payment.
Be Smart About Taxes
In India, a work bonus is fully taxable and is added to your salary, which could potentially push you into a higher tax bracket. Similarly, freelance income is taxable as 'Profits and Gains from Business or Profession'. For freelancers, the Presumptive Taxation Scheme under Section 44ADA is a simplified option if your gross receipts are below ₹50 lakh, allowing you to declare 50% of your income as profit. Understanding these tax implications is vital. Set aside money for taxes first, so the amount you allocate to your travel fund is what you truly have to spend. If your tax liability for the year exceeds ₹10,000, you will need to pay advance tax.
Stretch Your Travel Rupee
Once your savings plan is in motion, look for ways to make your travel fund go further. Consider travelling during the off-season when flights and hotels are cheaper. Choosing homestays or guesthouses over large hotels can also significantly cut costs and offer a more local experience. For transport within India, trains are often a more budget-friendly option than flights for long distances. Eating at local 'dhabas' or places where locals eat is not only more affordable but often a more authentic culinary experience. Every rupee saved on one part of your trip is another rupee you can spend on an experience that truly matters to you.
Track, Adjust, and Get Inspired
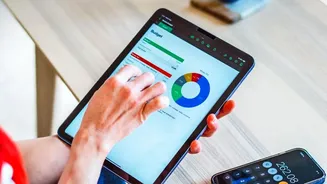
Regularly check in on your travel fund. Watching it grow is a reward in itself and will keep you motivated. Use a simple spreadsheet or a budgeting app to see how far you've come. This is also a good time to adjust your plan. If a freelance project paid more than expected, you might allocate extra to your fund to reach your goal faster. If expenses came up, you can adjust your timeline. Stay inspired by reading travel blogs, watching documentaries, or planning your itinerary. This keeps the end goal feeling real and exciting, making the discipline of saving feel less like a sacrifice and more like an investment in your future happiness.