

The Immediate Cost of Missed Payments
The most visible damage from unpaid credit card debt comes from immediate penalties. Missing a due date, even by a day, triggers a late payment fee. Following this, the bank begins charging high interest not just on the principal amount, but often on the entire
outstanding balance. Credit card interest rates are notoriously high, sometimes ranging from 3% to 4% per month, which can cause a small debt to balloon rapidly. Many users fall into the trap of only paying the minimum amount due. While this avoids a 'default' status for that month, the interest continues to pile up, making it incredibly difficult to clear the actual debt. This cycle of high interest and fees is the first and most direct way credit card debt begins to drain your financial resources.
The Silent Damage to Your CIBIL Score
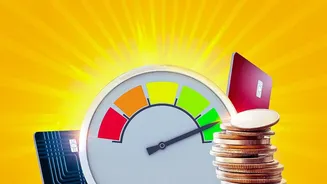
Beyond the financial costs, every missed payment deals a blow to your CIBIL score. In India, financial institutions report your payment behaviour to credit bureaus like TransUnion CIBIL. Your payment history is the single most important factor in calculating your score, accounting for a significant portion of it. A single late payment can be reported to the bureau and can cause your score to drop. A pattern of late payments or a high outstanding balance signals to lenders that you are a risky borrower. Even if you have a high credit limit, consistently using a large portion of it (a high credit utilisation ratio) can also lower your score, as it suggests a heavy reliance on credit. Ideally, you should aim to keep your credit usage below 30% of your available limit.
The Home Loan Hurdle
When you apply for a home loan, the lender's primary goal is to assess risk. The first thing they will check is your CIBIL score. Most lenders in India consider a score of 750 or above to be ideal for approving a home loan and offering the best interest rates. A score below 700 can lead to stricter conditions or outright rejection. Lenders will see a history of credit card defaults or high debt as a major red flag. It directly impacts your perceived repayment capacity. Even if your application is approved, a lower CIBIL score often results in a higher interest rate on the loan, which can translate into lakhs of rupees in extra payments over the life of the loan. In essence, the convenience of a credit card today could make your dream home significantly more expensive or even unattainable tomorrow.
Beyond the Home Loan
The dream of a home is not the only long-term goal affected by a poor credit history. A low CIBIL score creates obstacles across your financial life. You may find it difficult to get approved for other essential loans, such as a car loan or a personal loan for education or a family emergency. Even if you do get approved, the terms will likely be unfavorable. Furthermore, a bad credit history can impact other areas you might not expect. Some employers, particularly in the finance sector, may check credit histories during background checks. Landlords may also run a credit check before renting out a property, potentially leading to rejection or demands for a higher security deposit.
Rebuilding Your Financial Foundation
If you are struggling with credit card debt, the situation is not hopeless. The first step is to stop accumulating more debt and create a realistic budget. Focus on paying off your outstanding dues, starting with the card that has the highest interest rate. It is crucial to pay more than just the minimum amount each month. Make all future payments on time, as a consistent and clean payment history is the fastest way to begin repairing your CIBIL score. Regularly check your credit report for any errors and dispute them immediately. It takes time and discipline, but rebuilding your score is an essential step towards securing your long-term financial future.