



The New Financial Playbook
For many young Indians, the investment journey now starts not with a hot stock tip, but with a hard look at personal finances. Spurred by economic uncertainty and greater access to financial information online, many are realising that chasing high returns
without a safety net is like building a skyscraper on a foundation of sand. Financial planners and experts are increasingly advising a 'safety-first' approach. This doesn't mean avoiding risks, but preparing for them. The new playbook prioritises two foundational pillars before aggressively pursuing market growth: a robust cash buffer and comprehensive insurance coverage. This philosophy frames investing not as a gamble, but as the final step in a well-constructed financial plan.
Pillar 1: Building Your Cash Fortress
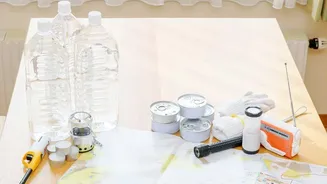
The first pillar is the emergency fund, a dedicated pool of money for unplanned life events. This isn't your vacation fund; it's a financial fire extinguisher for crises like a sudden job loss, an urgent medical bill not covered by insurance, or an essential home repair. Without this cash buffer, any unexpected expense can force you to sell your long-term investments at the worst possible time, potentially turning a temporary market dip into a permanent loss for you. Financial experts generally recommend an emergency fund that covers three to six months of your essential living expenses. This includes rent or EMIs, groceries, utility bills, and insurance premiums. For those with variable incomes, like freelancers or entrepreneurs, a larger buffer of nine to twelve months is often advised. The key is liquidity and safety; this money should be kept in a high-yield savings account or a liquid mutual fund, not in volatile assets like stocks.
Pillar 2: The Insurance Shield
The second pillar is insurance, which acts as a shield for your accumulated wealth. Many young professionals assume their employer-provided health cover is sufficient, but this coverage is often limited and disappears the moment you switch jobs. With medical inflation in India consistently outpacing general inflation, a single hospital stay can wipe out years of savings. A personal health insurance policy, purchased early in life when premiums are lower, provides a crucial layer of protection. Financial advisors often suggest a cover of at least Rs 10-15 lakh as a good starting point for a young professional. Alongside health insurance, term life insurance is vital, especially if you have financial dependents like parents or a spouse. It provides a substantial payout in the event of your untimely demise, ensuring your family's financial stability. Confusing insurance with investment is a common mistake; their purposes are distinct. Insurance is about protecting wealth, while investments are about creating it.
Safety First, Wealth Next
Adopting this foundational approach may seem 'boring' compared to the thrill of a rising stock market, but it is the secret to sustainable, long-term wealth creation. Having an emergency fund and adequate insurance provides profound peace of mind. It creates a stable base from which you can invest with confidence rather than anxiety. When you know an unexpected bill won't force you to liquidate your portfolio, you are better equipped to ride out market volatility and let the power of compounding work its magic. This financial discipline separates savvy investors from speculators. It transforms investing from a source of stress into a powerful tool for achieving your long-term goals, whether it's buying a home, funding your education, or retiring early. The foundation isn't about avoiding the game; it’s about ensuring you can stay in it for the long run.