The Hidden Cost of Convenience
For young earners, the first few years of a career are less about how much you earn and more about the financial habits you build. The problem with countless small UPI transactions is that they don't feel like real spending. A ₹150 food delivery or a ₹200
coffee doesn't trigger the same mental alarm as handing over physical cash. This phenomenon, sometimes called 'death by a thousand cuts', is where your budget is slowly drained by small, repetitive purchases that fly under the radar. Over time, these seemingly harmless habits—like impulse buys, unused subscriptions, and lifestyle inflation matching every pay rise—can evolve into significant financial patterns that prevent you from saving and investing effectively.
Your Spending Diary Is Already Written
The good news is, you don't need a complicated spreadsheet to start. Your spending diary is already being maintained for you inside your UPI app. Whether you use Google Pay, PhonePe, Paytm, or another app, your entire transaction history is just a few taps away. Take a moment to open your app and navigate to the 'History' or 'Transactions' section. Scroll back 30 days. This simple list is a powerful mirror reflecting your true spending habits, far more accurate than what you might guess. Most UPI apps even offer built-in features that categorise your spending, giving you an instant summary of where your money is going.
From Data to Diagnosis: What to Look For
As you review your transaction history, don't just look at the total amount spent. Instead, look for patterns. A great technique is to ask "How many times did I spend?" rather than "How much did I spend?". Sixteen food deliveries or twelve cab rides tell a more powerful story than the individual amounts. Search for the names of merchants that appear frequently. You might think you order from a quick-commerce app 'once in a while', but the data may show 15 transactions this month. Numbers are harder to argue with than vague feelings. Also, look for emotional triggers. Do online shopping sprees happen late at night or after a stressful week at work? Recognising these patterns is the first step toward conscious spending.
Creating a Simple, Actionable Budget
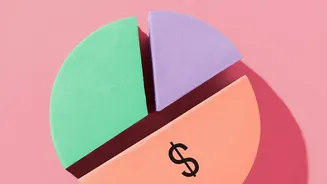
Once you have an honest picture of your spending, you can create a simple plan. A popular and effective method for beginners in India is the 50/30/20 rule. Allocate 50% of your take-home income to 'Needs' (rent, groceries, utilities), 30% to 'Wants' (dining out, shopping, hobbies), and 20% to 'Savings and Investments'. This framework provides a clear structure for your money. The goal isn't extreme restriction, but intentional spending. By identifying where you can cut back on 'Wants'—for instance, by reducing the number of food deliveries you identified earlier—you can free up more money for your financial goals.
Making Your New Habits Stick
The key to long-term financial health is consistency. One of the most effective strategies is to 'pay yourself first'. As soon as you receive your salary, automate the transfer of your 20% savings portion to a separate savings account or an investment like a Systematic Investment Plan (SIP). This ensures you save before you have the chance to spend. Another helpful tip is to create a separate bank account linked to your UPI for daily discretionary spending. Transfer a fixed amount into it each month to act as your 'Wants' budget, making it easier to track and control impulse purchases. Some people also find success using third-party expense tracker apps that can automatically log UPI payments by reading SMS alerts or confirmation screens, offering even more detailed analytics.