

Create Your Diwali Financial Blueprint
The most effective way to manage festive spending is to create a budget before you buy a single item. Start by listing all expected expenses: gifts for family and friends, new clothes, home decorations, sweets, travel, and any parties you plan to host.
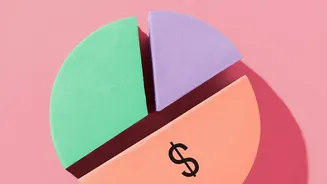
Assign a realistic amount to each category. This isn't about restriction; it's about gaining control. Once you have a total figure, compare it with the funds you have available. A common rule of thumb is the 50/30/20 festive budget: allocate 50% to must-haves like essential gifts, 30% to wants like new outfits, and keep 20% as a buffer for unexpected costs. This simple plan acts as your financial roadmap through the festive season.
Build a Dedicated Festive Fund
Ideally, Diwali expenses shouldn't come as a surprise from your October salary. The most stress-free way to pay for the festivities is to plan ahead. Many financial experts recommend creating a dedicated 'festive fund' months in advance. By setting aside a small amount, say ₹3,000 to ₹5,000, each month starting from June or July, you can build a substantial corpus by the time Diwali arrives. You can use a recurring deposit or simply a separate savings account for this. If you receive a festive bonus, resist the urge to spend it all. A smart approach is to allocate a portion for spending and invest the rest. Celebrating with money you have intentionally saved feels far more joyful than celebrating on credit.
Master the Art of Smart Shopping
Once you have a budget, the next step is to shop wisely. Always start with a detailed shopping list and stick to it to avoid impulse buys, which are often the biggest drain on a festive budget. Before making any large purchases, compare prices online and across different stores. Festive sales can offer great deals, but they can also encourage unnecessary spending. Use them to buy items that are already on your list at a lower price. It’s also wise to get your shopping done early, as prices for many items tend to increase closer to the festival. Prioritising your purchases—buying essential items first and then moving to non-essentials if the budget allows—is a crucial strategy.
Navigate Credit and BNPL Carefully
Plastic money and 'Buy Now, Pay Later' (BNPL) schemes make it easy to overspend because you don't feel the immediate impact of the expense. While credit cards offer rewards and cashback, they should be used with caution. A good rule is to only charge what you can afford to pay back in full when the bill arrives. BNPL can be even riskier. Marketed as a convenient, interest-free option, it can quickly become a debt trap with high late fees and a negative impact on your credit score if payments are missed. Some experts suggest using cash or your debit card for festive shopping to stay aware of your spending in real time. When your cash runs out, you know you've hit your limit.
Track Your Spending in Real Time
A budget is only useful if you follow it. The easiest way to stay on track is to monitor your spending as it happens. You can use a simple notebook or a budgeting app to log every purchase. Many modern apps designed for Indian users, like INDMoney, Monefy, or Spendee, can help you categorise expenses and see where your money is going at a glance. Some apps can even automatically track your UPI and card transactions from your SMS inbox, making the process effortless. Regularly checking your spending against your budget allows you to make adjustments on the fly and prevents the dreaded end-of-month surprise when you realise you've spent far more than you intended.