
Money Is Now Invisible
In a world dominated by digital transactions, the concept of money has become less tangible for children. Unlike previous generations who saw physical cash exchanged for goods, today’s youth often witness seamless, invisible payments. This can make it difficult
for them to grasp fundamental concepts like value, spending, and the fact that money is a finite resource. When a child sees a parent simply tap a card, they don't witness the balance decreasing, which can create the illusion of an infinite supply. This disconnect is a major driver for parents to proactively explain what is happening behind the screen, making the invisible visible through conversation and practical examples.
A More Complex Financial World
The financial landscape that today's children will inherit is vastly more complicated. They will navigate everything from student loans and credit card debt to mobile banking apps, online investing platforms, and even cryptocurrencies. Without a foundational understanding of concepts like interest, budgeting, and debt, they can easily be overwhelmed or make costly mistakes. Studies show that money habits begin to form as early as age seven. By introducing simple financial ideas early on, parents are equipping their children with the tools to make informed and responsible decisions later in life. This isn't about teaching them to become financial experts overnight, but about building a framework of confidence and competence.
Changing Economic Realities
The days of guaranteed pensions and lifelong job security are fading. The modern economy places a greater emphasis on individual financial responsibility for long-term security. Families recognise that their children need to be self-reliant and prepared for a future where they will be the primary architects of their financial well-being. This involves understanding how to save for retirement, build an emergency fund, and navigate a more flexible and sometimes less predictable world of work. Teaching children to save and budget from a young age fosters discipline and delayed gratification, crucial skills for weathering life's inevitable financial ups and downs. It is a direct response to a world that demands more financial foresight from everyone.
Building Healthy Habits and Well-being
Financial literacy is more than just numbers; it's about behaviour and emotional health. Early money lessons are a powerful way to instill habits that reduce future stress and anxiety. When children learn to distinguish between 'wants' and 'needs', set savings goals, and practice patience, they are building a foundation for financial stability. This proactive education helps prevent common pitfalls like impulse spending and accumulating high-interest debt. Furthermore, research has shown a link between financial literacy learned in youth and healthier romantic relationships in adulthood, as good money management habits can lead to less financial conflict. By talking openly about finances, parents are not just teaching a practical skill, they are promoting a lifetime of better decision-making and personal well-being.
How Families Are Starting the Conversation
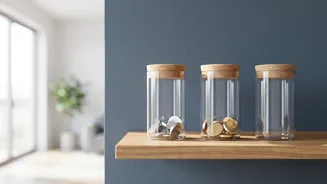
Recognising that schools may not cover this topic sufficiently, many parents are taking the lead. The approach doesn't have to be complex. It starts with simple, age-appropriate actions. For younger children, using a clear jar instead of a piggy bank helps them physically see their savings grow. Involving kids in everyday financial activities, like comparing prices at the grocery store or discussing household bills in simple terms, makes money a normal part of conversation. Giving a small allowance tied to chores teaches them about earning, and encouraging them to divide it into jars for spending, saving, and giving introduces the concept of budgeting. These small, consistent lessons demystify finance and empower children, turning a potentially intimidating subject into a familiar life skill.