


The All-Important Mindset Shift
The core difference between saving and investing lies in purpose and risk. Saving is about parking money in a safe place, like a bank account, for short-term goals or emergencies. It’s low-risk but also offers low returns, often not even keeping pace
with inflation. Investing, on the other hand, is the act of putting your money into assets like mutual funds or stocks with the expectation of generating higher returns over the long term. It involves taking on calculated risks to grow your wealth and achieve significant financial goals like buying a home or planning for retirement.
Before You Invest: Lay the Foundation
Excitement to start investing is great, but a few prerequisites will ensure you’re building on solid ground. First, create an emergency fund. This should be a sum equivalent to three to six months of your living expenses, kept in a highly accessible savings account. This fund acts as your financial safety net, preventing you from having to sell your investments during an unexpected crisis. Second, if you have high-interest debt, like from credit cards, focus on clearing that first. The interest you pay on such debt is often far higher than the returns you can realistically expect from initial investments.
What's Your Risk Appetite?
Investing always involves some level of risk. Understanding your personal risk tolerance is crucial before you choose where to put your money. This depends on your age, financial goals, and how comfortable you are with potential market fluctuations. A young person with a long career ahead can generally afford to take on more risk for potentially higher returns, as they have more time to recover from any market downturns. Someone closer to retirement would likely prefer more stable, lower-risk options. Being honest about your risk appetite will help you build a portfolio that lets you sleep at night.
Your First Steps into the Investment World
For young investors in India, the options have never been more accessible. You don't need a large sum to begin. One of the most recommended starting points is a Systematic Investment Plan (SIP) in a mutual fund. A SIP allows you to invest a small, fixed amount regularly, such as every month. This approach instils discipline and benefits from rupee cost averaging, where you buy more units when the market is low and fewer when it's high. Equity mutual funds are a popular choice for long-term growth. Other beginner-friendly options include Index Funds, which track a market index like the Nifty 50, Public Provident Fund (PPF) for long-term, government-backed savings, and digital gold.
The Magic of Compounding and Consistency
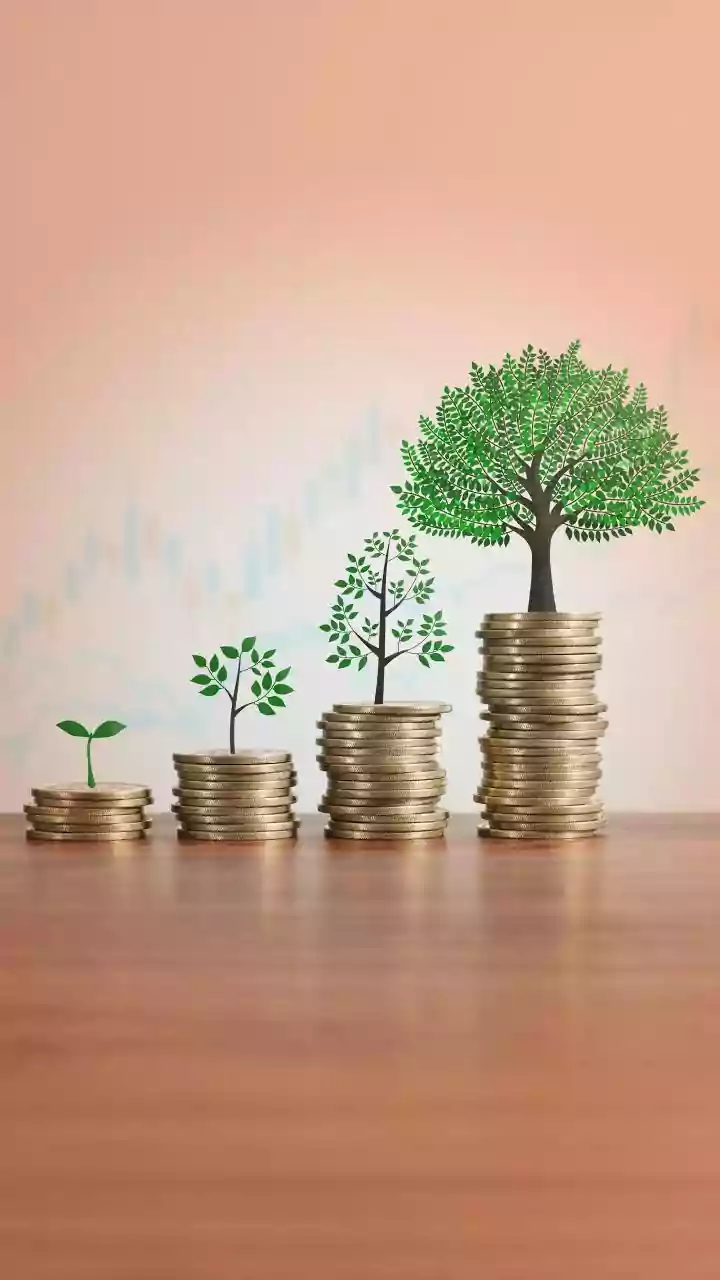
The single biggest advantage a young investor has is time. Starting early allows you to harness the power of compounding, where your returns start generating their own returns. A small amount invested regularly in your 20s can grow into a much larger corpus than a bigger investment started in your 30s or 40s. A SIP is the perfect tool to leverage this. By investing a consistent amount each month, you build a disciplined habit and allow compounding to work its magic over decades. The key is not to chase quick profits but to stay invested for the long run.
Common Mistakes to Sidestep
As you begin your journey, be aware of common pitfalls. One is trying to 'time the market'—predicting highs and lows to buy and sell. This is nearly impossible to do consistently, and a disciplined, regular investment approach usually yields better results. Another mistake is a lack of diversification, or putting all your money in one place. Spreading your investments across different assets reduces risk. Finally, avoid making decisions based on hype or herd mentality. Do your own research or consult an advisor to ensure your choices align with your personal financial goals.