
Physical Gold: The Traditional Touch
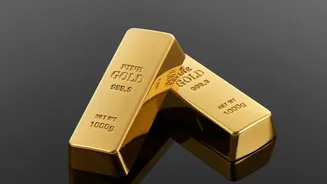
This is the gold you can see and hold—jewellery, coins, and bars. Its biggest advantage is its tangibility and cultural significance; it can be worn, gifted, and passed down through generations. There is no counterparty risk, meaning your ownership isn't
dependent on a financial institution's stability. However, this traditional route comes with significant drawbacks for the pure investor. Making charges on jewellery can range from 8% to over 25%, a cost you never recover on resale. Then there are storage costs for bank lockers, which can range from ₹2,000 to ₹15,000 annually, plus the constant worry of theft. Purity can also be a concern, and when you sell, jewellers often deduct for wastage, further reducing your returns. A 3% Goods and Services Tax (GST) is also levied on the purchase value.
Digital Gold: The Modern Convenience
Offered by fintech platforms, digital gold allows you to buy 24-karat gold online in small increments, sometimes for as little as ₹1. The gold is physically stored in insured vaults by a custodian, saving you the hassle of storage and security. It’s convenient, highly liquid, and can be bought or sold instantly through an app. However, this convenience comes with critical risks. Digital gold is largely unregulated in India, meaning it falls outside the direct oversight of SEBI or the RBI. This lack of a regulatory framework exposes investors to counterparty risk; if the platform or its vaulting partner fails, you could lose your entire investment. Furthermore, there's often a 2-5% spread between the buy and sell price, acting as a hidden fee. Like physical gold, a 3% GST is charged on every purchase, which is non-recoverable. Most platforms also have a limited holding period, after which you must either sell or take physical delivery.
Sovereign Gold Bonds (SGBs): The Investor’s Choice
SGBs are government securities issued by the Reserve Bank of India (RBI) that are denominated in grams of gold. They are considered the safest option as they are backed by the Government of India, eliminating counterparty risk. SGBs offer two distinct advantages over other forms of gold. First, they pay a fixed interest of 2.5% per year on the initial investment value, paid semi-annually. Second, if held until the full maturity of eight years, any capital gains are completely tax-free for individual investors who subscribed during the initial issuance. There are no making charges or GST on purchase, though those buying online receive a discount. The main limitations are liquidity and availability. SGBs have a tenure of eight years, with an option for early exit from the fifth year onwards. While they are tradable on stock exchanges after an initial lock-in period, liquidity can sometimes be low.
Which Gold Is Right For You?
Choosing the best form of gold depends entirely on your financial goals. If your primary purpose is for personal use, consumption, or gifting, physical gold remains unparalleled due to its tangible and emotional value, despite its high costs. If you are looking for a short-term, convenient way to trade gold in very small amounts and are comfortable with the regulatory risks, digital gold might seem appealing. However, for a pure, long-term investment aimed at wealth creation, Sovereign Gold Bonds are superior. They offer capital appreciation linked to gold prices, provide an additional interest income, and come with significant tax benefits and government-backed security. The absence of entry costs like making charges and GST further enhances their return potential compared to both physical and digital gold.