

The Squeeze on Your Wallet
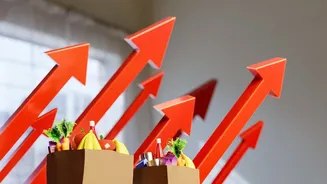
The consistent rise in the cost of daily essentials is no longer a temporary trend but a reality Indian households are grappling with. Recent data from October 2026 highlights the dual pressure of food and energy inflation. The Reserve Bank of India (RBI)
has noted that inflation is a significant concern, raising its forecast for the financial year. Food inflation, in particular, has become a major driver, with projections for September showing a sharp acceleration, pushed by rising prices of vegetables, pulses, and cereals. This is compounded by factors like a deficient monsoon and ongoing global supply chain disruptions. Households are reporting heightened anxiety about living costs, with inflation expectations for the year ahead reportedly climbing.
Where Prices Are Pinching Most
The impact is felt most acutely in non-discretionary spending. Food items like vegetables have seen significant price jumps, with some estimates suggesting a nearly 34% rise in onion prices in a single month. Economists expect food inflation to remain elevated, potentially crossing 7% in the coming months. Simultaneously, energy costs continue to be a burden. While prices for petrol and diesel at the pump for consumers have remained largely stable recently due to state-run companies absorbing costs, the underlying international prices are high. However, commercial LPG costs have seen increases, which indirectly affects the cost of goods and services, like eating out. For the average family, this translates to less purchasing power, meaning the same amount of money buys fewer goods and services than it did before.
Why Your Old Budget Is Now Obsolete
In a high-inflation environment, a 'set it and forget it' approach to your finances is a recipe for stress. A budget created even six months ago may no longer reflect the reality of your expenses. When the cost of necessities like food, transport, and cooking gas rises faster than your income, your ability to save and spend on discretionary items like entertainment or travel is severely eroded. Relying on a fixed mental budget can lead to a gradual increase in debt, often through credit cards, just to maintain a lifestyle. This is why a reactive approach is insufficient; what's needed is a proactive, regular review of your financial situation.
Your First Step: Track Every Rupee
The first and most powerful step towards taking control is to understand exactly where your money is going. This doesn't have to be complicated. You can use a dedicated budgeting app, a spreadsheet, or even a simple notebook. For one full month, track every single expense, from your morning cup of tea to your utility bills and loan EMIs. Categorise these expenses into 'Needs' (groceries, rent, transport to work) and 'Wants' (dining out, subscriptions, shopping). This exercise isn't about judging your spending; it's about creating a clear, factual picture of your financial flow. This data is the foundation upon which all other financial decisions will be built.
Analyse and Identify Areas for 'Smart Savings'
Once you have a month's worth of data, sit down and analyse it. Where are the biggest leaks? Often, small, frequent purchases in the 'Wants' category add up to a surprising amount. Look for opportunities for 'smart savings'—not about deprivation, but about making conscious choices. Can you switch to cheaper substitutes for some grocery items? Could you cancel a streaming subscription that you rarely use? Planning meals for the week can drastically reduce impulse food orders and grocery waste. The goal is to redirect money from low-priority 'Wants' towards covering the rising cost of 'Needs' and bolstering your savings.
Make Budgeting a Monthly Ritual
The final, and most crucial, step is to make this review process a habit. Set aside an hour on the same day each month to go over your expenses, check in on your savings goals, and adjust your plan for the month ahead. This regular check-in allows you to be agile. If you know fuel prices are expected to rise, you can budget for it. If you have a big expense coming up, you can plan cuts elsewhere. A monthly review turns your budget from a rigid set of rules into a dynamic tool that helps you navigate economic uncertainty with confidence and control. It helps you prepare for continued price pressures and protects your long-term financial stability.