


From Bahi Khata to Digital Ledger
The traditional bahi khata, a physical ledger book, has long been the backbone of credit and accounting for India's ubiquitous kirana stores. This manual system, while time-tested, is prone to human error, can be easily lost or damaged, and makes tracking
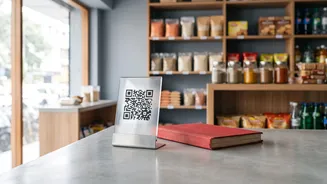
dues a laborious task. The rise of digital payments, spearheaded by the Unified Payments Interface (UPI), is fundamentally altering this dynamic. When a customer pays via a QR code, the transaction is automatically recorded. This simple act creates a digital footprint, shifting bookkeeping from a manual, end-of-day chore to an automated, real-time process. Apps designed for small businesses, often called digital 'khatas', integrate with these payments, creating a seamless flow of information from the point of sale directly into the shop's financial records.
The Power of Automatic Reconciliation
One of the most significant changes for shopkeepers is the drastic reduction in manual reconciliation. Digital payment systems automate data capture, which minimizes mistakes that are common in manual bookkeeping. Instead of manually tallying cash sales against a physical ledger, merchants can now see a clear, itemised list of every digital transaction. This instant record-keeping helps in matching sales to payments, reducing discrepancies and saving hours of work. For businesses, this means improved operational efficiency; some reports suggest merchants save significant time previously spent on bank visits for cash deposits and manual counting. Furthermore, these digital records are invaluable for compliance, making it easier to generate reports for GST filing and other financial assessments.
Beyond Convenience: Unlocking Access to Credit
Perhaps the most transformative impact of digital bookkeeping is its ability to unlock formal credit for Micro, Small, and Medium Enterprises (MSMEs). India's MSME sector has historically faced a massive credit gap, with many businesses unable to access formal loans due to a lack of collateral or verifiable financial history. Digital transaction records provide exactly that—a verifiable, data-driven trail of a business's cash flow. Lenders can use this digital payment history to assess creditworthiness, moving away from traditional collateral-based models to cash-flow-based underwriting. This has enabled fintech companies and banks to offer small-ticket loans and 'Buy Now, Pay Later' products tailored for small merchants, helping them manage working capital, purchase inventory, and grow their business. The formalisation of transaction data turns a simple payment record into a powerful tool for financial inclusion.
New Hurdles on the Digital Frontier
Despite the clear benefits, the transition is not without its challenges. For many small merchants, a lack of awareness about how digital payment systems fully work can be a barrier. Issues like digital illiteracy, inconsistent internet connectivity, especially in rural areas, and language barriers can hinder adoption. Fear of fraud and a lack of trust in digital systems also play a role, as many micro-merchants are accustomed to handling cash. Furthermore, while many UPI transactions remain free for consumers and small merchants, the introduction of Merchant Discount Rates (MDR) on certain higher-value transactions is a concern. As of late 2026, while transactions up to ₹2,000 and for small merchants below a certain threshold remain free of MDR, charges apply to larger transactions, which could impact profitability for some businesses.