
A Modern Twist on an Old Habit
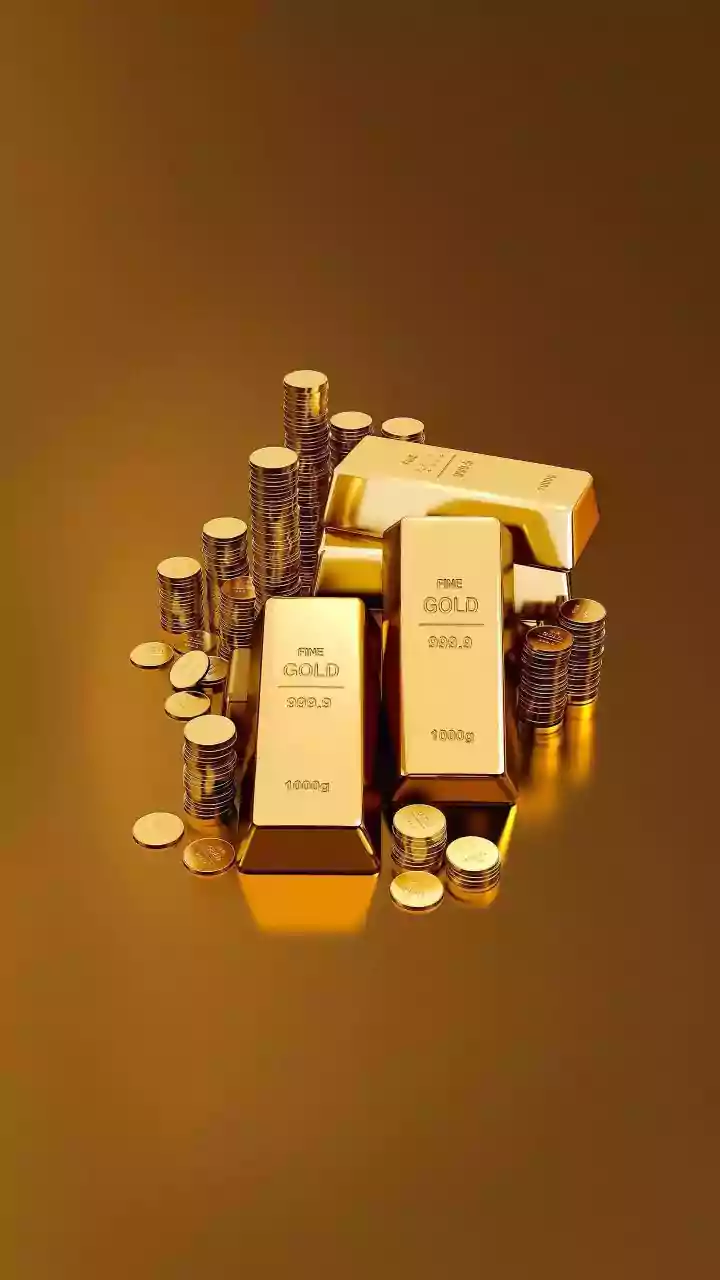
Digital gold is an online method of buying pure 24-karat gold without the need to physically hold it. When you invest through a fintech app, your money buys a corresponding amount of physical gold, which is then stored in a secure, insured vault by the provider,
such as MMTC-PAMP or SafeGold. You own the gold and can sell it anytime at live market rates or, in many cases, have it delivered as coins or bars. This blend of traditional asset ownership with modern convenience is proving to be a powerful draw for a generation that manages its finances on a smartphone.
The Power of Small, Systematic Sips
The single biggest reason for the popularity of digital gold among young savers is the ability to invest incrementally. Platforms allow users to buy gold for amounts as low as ₹1 or ₹10, removing the large financial barrier associated with traditional gold purchases. This transforms gold ownership from a one-time, high-value transaction into a disciplined savings habit, much like a Systematic Investment Plan (SIP) for mutual funds. By investing small, fixed amounts regularly, savers can average out their purchase price over time, reducing the risk of buying at a market peak. This 'sachet-sized' approach to a precious metal makes it accessible for students, young professionals, and anyone starting their investment journey.
Convenience, Purity, and Price Locking
Beyond affordability, digital gold offers unparalleled convenience. Investors can buy or sell 24/7 from anywhere using payment methods like UPI, without visiting a jeweller or worrying about storage and security. This addresses major pain points associated with physical gold. Furthermore, digital gold is always certified 24K, with a purity of 99.5% or higher, eliminating concerns about quality that can arise with jewellery. Each purchase locks in the gold price at that exact moment for the quantity bought, offering transparency that is often missing in the physical market. Crucially, it bypasses making charges, which can range from 10-25% on jewellery and are typically non-recoverable upon sale.
What to Watch For: Costs and Regulation
Despite its advantages, digital gold is not without its costs and risks. Every purchase incurs a 3% Goods and Services Tax (GST), similar to physical gold. Platforms also have a 'spread'—a difference of 2-5% between the buying and selling price, which can result in an immediate small loss if you sell quickly. Some providers may also charge storage fees after an initial free period. The most significant concern, however, is the lack of direct regulation. In November 2025, the Securities and Exchange Board of India (SEBI) clarified that digital gold is not a regulated security, meaning investors do not have access to the same grievance redressal mechanisms as they would with stocks or mutual funds. While the government is reportedly considering a regulatory framework, for now, the safety of the investment depends on the credibility of the platform and its vaulting partners.
How It Compares to Other Gold Investments
For an investor, it's important to know where digital gold fits. Gold Exchange-Traded Funds (ETFs) are a regulated alternative that trades on stock exchanges and requires a Demat account. They often have lower costs (expense ratios) and no GST on purchase, making them suitable for larger, portfolio-style investments. Sovereign Gold Bonds (SGBs), issued by the RBI, are another government-backed option. They offer tax-free capital gains at maturity (after 8 years) and a 2.5% annual interest, but they have a long lock-in period and are not as liquid as digital gold or ETFs. Digital gold's niche is its extreme accessibility and flexibility for small, casual, or habit-based investing without needing a Demat account.