

Gold loans offer a quick way to access funds, but the process can be confusing. Understanding how your jewellery is valued and what fees you'll pay is crucial to avoid surprises and ensure you get a fair deal on your valuable asset.
How Lenders Value Your Gold
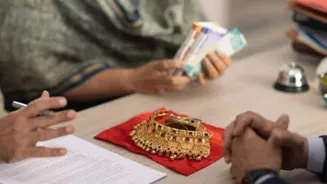
The first step in any
gold loan is the valuation of your jewellery, and this is where much of the confusion begins. Lenders do not consider the price you paid for the ornament, including making charges or GST. Instead, their assessment is based on three key factors: purity, weight, and the current market rate of gold. Purity is measured in carats (K), with most lenders accepting jewellery between 18K and 22K. A higher carat means higher purity and, therefore, a higher valuation. Appraisers use tools like karat meters to determine the exact purity. Next, they calculate the net weight of the gold. Any stones, gems, enamel, or other non-gold materials are excluded from this calculation. Finally, this net weight is multiplied by the prevailing gold rate. As per RBI guidelines, lenders typically use the average gold price over the last 30 days to ensure fairness and protect against daily price fluctuations.
Understanding the Loan-to-Value Ratio
Once your gold's value is determined, the lender will not offer you the full amount as a loan. They apply a Loan-to-Value (LTV) ratio, which is the percentage of the gold's assessed value you can borrow. The Reserve Bank of India (RBI) sets the maximum LTV to manage risk for both lenders and borrowers. Recently, the RBI introduced a tiered structure. For smaller loans up to ₹2.5 lakh, borrowers can get a higher LTV of up to 85%. For loans between ₹2.5 lakh and ₹5 lakh, the LTV is capped at 80%, and for loans above ₹5 lakh, it remains at the standard 75%. This means if your gold is valued at ₹1 lakh and you are eligible for a 75% LTV, the maximum loan amount you can receive is ₹75,000. The remaining 25% acts as a safety margin for the lender in case gold prices fall.
Decoding the Processing Fee
The most common upfront cost is the processing fee. This one-time charge covers the administrative expenses of setting up your loan, including application handling, verification, and documentation. This fee can be structured as a flat amount or, more commonly, as a percentage of the sanctioned loan amount, typically ranging from 0.25% to 2%. For a loan of ₹1 lakh, a 1% processing fee would mean an additional cost of ₹1,000 plus GST. Some lenders might offer waivers or have nominal flat fees, especially for smaller loan amounts, so it's always worth asking. For instance, some banks offer zero processing fees for loans up to a certain amount.
Watch Out for Other Charges
Beyond the processing fee, several other charges can add to the total cost of your loan. A valuation or appraisal fee, often between ₹200 and ₹500, may be charged separately for the service of assessing your gold. If you decide to repay your loan before the agreed tenure, you might face foreclosure or prepayment charges, which can be up to 2% of the outstanding amount, although some lenders waive this fee after a certain lockin period. Missing a payment can result in late payment penalties. In the unfortunate event of a default leading to an auction of your gold, you could also be liable for auction_related charges. Additionally, stamp duty may be applicable depending on the state's laws. Always check if quoted fees are inclusive or exclusive of GST, as this can affect the final amount you pay.
Your Pre_Loan Checklist
To avoid any unwelcome surprises, approach the loan process with a clear checklist. Before committing to a lender, ask for a complete and detailed schedule of all applicable fees, not just the headline interest rate. Compare the processing fee structures—a flat fee might be better for a large loan, while a percentage_based fee is often more suitable for a smaller one. Enquire about prepayment penalties and the lockin period. Understand the lender’s policy on late payments and other potential charges. By comparing offers from multiple lenders, including banks and NBFCs, and carefully reading the loan agreement, you can ensure the terms are transparent and favourable. This diligence will empower you to choose a loan that truly meets your needs without incurring unexpected costs down the line.