

The Revolution in a Billion Pockets
The engine behind India's digital payment explosion is the Unified Payments Interface, or UPI. Launched in 2016, it’s a government-backed system that turned complex bank transfers into something as simple as sending a text message. Unlike credit card
systems that were slow to spread, UPI was built for the mobile-first reality of modern India. It’s an open platform, meaning dozens of apps like Google Pay, PhonePe, and Paytm can all use it to talk to each other and to nearly every bank in the country. This interoperability, combined with some of the world's cheapest data plans and widespread smartphone use, created a perfect storm. The COVID-19 pandemic acted as a massive catalyst, pushing even the most reluctant merchants and consumers toward contactless payments. Suddenly, a system that was a mere convenience became an essential service.
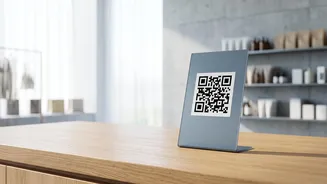
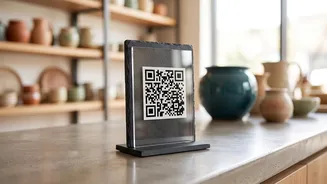
The QR Code on Every Corner
For India’s millions of micro, small, and medium enterprises (MSMEs)—which form the backbone of the economy—the shift has been transformative. The most visible change is the speed and ease of transactions. There’s no more fumbling for change or losing a sale because a customer is short on cash. This has led to reported increases in sales for many small vendors. Beyond convenience, going digital creates an automatic financial record. The traditional 'bahi-khata', or physical ledger, is being replaced by a digital trail. This is a game-changer for accessing credit. For generations, a small shop owner with no formal records would struggle to get a bank loan. Now, fintech lenders can analyze a business's digital transaction history to assess creditworthiness, opening up new avenues for funding and growth that were previously unimaginable.
New Hurdles and Hidden Costs
But the transition isn't without its challenges. The most significant hurdles are digital literacy and infrastructure. In many rural and semi-urban areas, unreliable internet connectivity can bring business to a halt. Furthermore, not every shop owner is comfortable navigating digital apps, and concerns about online fraud and cybersecurity are very real. Then there's the cost. While many everyday UPI transactions are free for consumers and small merchants, a Merchant Discount Rate (MDR), or transaction fee, does apply to certain larger payments. Though government rules aim to protect the smallest businesses from these fees, the debate over who should bear the cost of maintaining this massive digital infrastructure—merchants, consumers, or banks—is ongoing. For businesses operating on razor-thin margins, even small fees can make a difference.
More Than Just a Payment
The adaptation to digital payments is evolving from a simple transaction tool into a deeper integration with business operations. Small retailers now connect WhatsApp ordering with instant UPI payment links, turning a neighborhood shop into a local delivery service. The data generated by these payments provides powerful insights into sales trends and customer behavior, allowing even the smallest vendors to make smarter decisions about inventory and pricing. This formalization of the economy, moving businesses from the untraceable world of cash to the documented world of digital, also helps with tax compliance and overall financial management. It represents a fundamental shift in how business is done, bringing millions of small entrepreneurs into the formal economy for the first time.