





Beyond the Monthly Payment
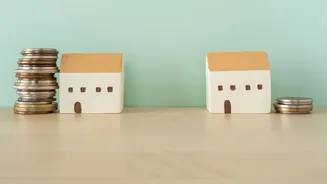
For years, the core of the rent-or-buy question was simple: if the Equated Monthly Instalment (EMI) on a home loan was close to the monthly rent, buying seemed like the logical step. This thinking, however, overlooks a mountain of other costs associated
with homeownership. The conversation is now expanding to include a host of other financial considerations that have a significant impact on your long-term wealth. These include substantial one-time costs, recurring expenses beyond the EMI, and crucial concepts like opportunity cost.
The Hidden and Recurring Costs of Ownership
The price a builder advertises is just the base cost. On top of this, a buyer in India must budget for a significant number of additional expenses. These upfront costs include stamp duty (which can be 5-7% of the property value), registration charges (around 1%), and GST on under-construction properties. Furthermore, there are legal fees, charges for preferential locations (PLC), floor rise, parking, and home loan processing fees. Together, these can inflate the initial cost by 15-25% or more. But the expenses don't stop there. Once you own the home, you are responsible for recurring costs like annual property taxes, society maintenance charges, and funds for repairs and insurance, all of which are expenses a renter typically doesn't bear.
The Crucial Question of Opportunity Cost
Perhaps the most overlooked factor is the opportunity cost of the down payment. This is the potential return you could have earned if you had invested that large sum of money elsewhere, for instance, in mutual funds or stocks. A down payment of ₹20 lakh, for example, is not just ₹20 lakh; it's also the potential growth of that money over 15 or 20 years, which could be substantial. Financial planners now argue that a true comparison must pit the total cost and appreciation of a home against a renter's scenario where the down payment and the monthly savings (the difference between EMI and rent) are invested wisely. Ignoring this makes property returns seem better than they might actually be.
Flexibility vs. Stability
The decision also hinges on your lifestyle and career stage. Renting offers immense flexibility. For those with dynamic careers or who may need to relocate, being tied to a property can be a significant burden. Selling a property is an illiquid process that takes time and incurs its own costs. On the other hand, buying a home offers stability, a sense of security, and the freedom to create your own space without a landlord's restrictions. It forces a form of savings through the monthly EMI, which helps build a tangible asset over the long term. This emotional and psychological benefit of ownership is a valid, though non-financial, part of the calculation.
A New Framework for Your Decision
So, how should you decide? First, honestly assess how long you plan to stay in one location; buying makes more financial sense over a longer horizon, typically seven years or more. Second, calculate the price-to-rent ratio in your area by dividing the property's price by the annual rent. A high ratio (above 25) suggests that renting is likely the cheaper option financially. Finally, instead of just comparing EMI to rent, compare the total cost of ownership (including all hidden fees and recurring costs) to the total cost of renting plus the potential returns from investing your savings. This comprehensive view will give you a much clearer picture of what's truly best for your financial future.