

The Problem with a Single Fixed Deposit
Fixed Deposits (FDs) are a cornerstone of safe investing in India, offering capital protection and predictable returns. Many beginners start by putting a lump sum into a single FD for a long tenure to get a good interest rate. However, this simple approach
has two major drawbacks. First is the lack of liquidity. Your money is locked in for the entire duration. If an unexpected expense arises, breaking the FD prematurely often results in a penalty, typically 0.5% to 1% of the interest rate. Second is interest rate risk. If you lock in your funds for five years and interest rates rise in the second year, your investment is stuck earning the older, lower rate.
The Laddering Strategy Explained
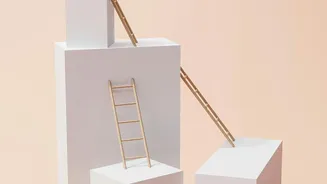
FD laddering solves these problems by not putting all your eggs in one basket. It's a strategy where you divide your total investment into several smaller Fixed Deposits with different maturity dates. Instead of one large FD, you create a 'ladder' of FDs that mature at regular intervals—for example, every year. This staggered structure ensures you have access to a portion of your funds periodically without disturbing your entire investment. As each FD matures, you can either use the money for a planned expense or reinvest it, which keeps the ladder going.
How to Build Your First FD Ladder
Building an FD ladder is more straightforward than it sounds. Let's take an example. Suppose you have ₹5 lakh to invest. Instead of a single ₹5 lakh FD for five years, you can split it up. Step 1: Divide your corpus into five equal parts of ₹1 lakh each. Step 2: Open five separate FDs with staggered tenures. You would create: FD 1: ₹1 lakh for 1 year. FD 2: ₹1 lakh for 2 years. FD 3: ₹1 lakh for 3 years. FD 4: ₹1 lakh for 4 years. FD 5: ₹1 lakh for 5 years. At the end of the first year, FD 1 matures. If you don't need the cash, you can reinvest that ₹1 lakh (plus interest) into a new 5-year FD. The next year, FD 2 matures, and you do the same. After a few years, you'll have a rolling system where one FD matures every single year, giving you both liquidity and the benefit of longer-term interest rates.
The Three Core Benefits for Beginners
This strategy is essential for beginners because it perfectly balances three key financial needs. The first is enhanced liquidity. Since an FD matures every year, you have predictable access to cash for goals or emergencies, avoiding premature withdrawal penalties. The second is mitigating interest rate risk. With a ladder, only a portion of your money is up for renewal at any given time. If rates have gone up, you can reinvest the maturing FD at the new, higher rate. If rates have fallen, the rest of your FDs are still locked in at their original, higher rates. The third is creating discipline. The regular, structured nature of the ladder helps new investors learn cash flow planning and the habit of systematic reinvestment.
Is This the Right Strategy for You?
FD laddering is ideal for conservative investors, those nearing retirement, or anyone building a stable financial foundation. It is an excellent way to structure an emergency fund or save for predictable, medium-term goals like a down payment for a car or a planned vacation. However, it's important to acknowledge its limitations. The returns from FDs, even when laddered, may not beat inflation over the long run and will likely be lower than higher-risk investments like equities. The strategy also requires a bit more management than a single FD, as you need to track multiple maturity dates. For an investor prioritising safety and liquidity above all else, these trade-offs are often worthwhile.