


An Unstoppable Digital Revolution
The scale of India's UPI adoption is staggering. In just a decade since its launch in 2016, UPI has become the default payment method for millions. In July 2026 alone, the platform processed over 23.6 billion transactions worth nearly ₹30 lakh crore.
This explosive growth, fuelled by its simple, fast, and interoperable design, means that Person-to-Merchant (P2M) payments now make up the majority of transaction volume. For businesses, from the smallest street vendor to the largest retail chain, this rapid consumer shift has made accepting UPI non-negotiable.
Beyond the Basic QR Code
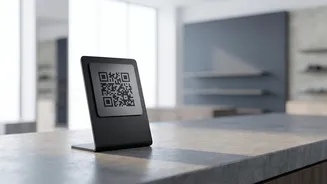
The most visible sign of adaptation is the ubiquitous QR code. For micro-merchants and small stores, the ability to accept digital payments without expensive Point of Sale (POS) machines has been a game-changer, democratizing access to the digital economy. However, more sophisticated businesses are moving beyond simple static QR codes. They are implementing dynamic QRs, which generate a unique code for each transaction with the amount pre-filled. This seemingly small step is crucial for automation, as it allows businesses to track sales accurately and simplifies the accounting process, eliminating the need for manual reconciliation.
Deep Integration into Operations
True adaptation goes deeper than just customer payments. Businesses are now integrating UPI into their core operational software. By connecting UPI payments directly to their POS and accounting systems, companies can achieve real-time sales tracking, automated inventory updates, and streamlined financial reporting. This integration reduces manual errors, improves cash flow management by ensuring faster settlements, and provides a clear, real-time view of the business's financial health. It marks a significant shift from merely accepting UPI to leveraging it for genuine operational efficiency.
Data as a Strategic Asset
Every UPI transaction creates a data point. Savvy businesses are beginning to realize that this digital footprint is an invaluable asset for understanding their customers. By analyzing transaction data (with customer consent and in compliance with privacy regulations), businesses can identify purchasing patterns, popular products, and peak sales times. This insight allows them to offer personalized discounts, create targeted loyalty programs, and make data-driven decisions about inventory and marketing. In essence, UPI is transforming from a simple payment channel into a rich source of business intelligence.
The Next Frontier: Credit and Value-Added Services
The UPI ecosystem is constantly evolving, and businesses are adapting to its newest features. The introduction of 'Credit on UPI' is a significant development, allowing customers to link pre-sanctioned credit lines to their UPI apps. For merchants, this means they can accept credit-based payments without a traditional POS machine, potentially increasing customers' purchasing power and boosting average ticket sizes. Furthermore, fintech companies are building value-added services on top of UPI, such as automated bookkeeping, inventory management, and even facilitating access to small business loans based on transaction history.
Navigating the Challenges
The transition isn't without its hurdles. Businesses face challenges such as transaction failures, the risk of digital fraud, and ensuring their systems are secure and compliant with RBI guidelines. For small vendors, there's a learning curve and the potential for confusion around tax compliance, as every digital transaction leaves a trail. There are also infrastructure gaps, especially in rural areas, where connectivity can be unreliable. Addressing these issues through staff training, customer education, and investing in reliable technology is a critical part of the adaptation process.