



What Exactly is Changing on October 15?
The National Payments Corporation of India (NPCI) is introducing a Merchant Discount Rate (MDR) of 0.4% on person-to-merchant (P2M) UPI transactions that are over ₹2,000. This isn't a blanket charge on all UPI use. Crucially, person-to-person (P2P) money
transfers—like sending money to a friend or family member—remain completely free, regardless of the amount. The new fee specifically targets commercial transactions where a customer pays a business. For example, a payment of ₹3,000 to a merchant would attract an MDR of ₹12, which is to be borne by the merchant. For very large transactions, this fee is capped at a maximum of ₹300, which applies to any payment of ₹75,000 or more.
Who Actually Pays This New Fee?
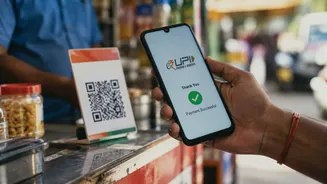
To be clear: customers will not be charged for making UPI payments. The MDR is a cost for the merchant who receives the payment. It's a fee paid by the business to their bank or payment service provider for the service of processing the digital transaction. The government and NPCI have been firm that merchants should not pass this cost on to consumers by adding a surcharge. The fee is designed to be absorbed by the business as an operational cost, similar to charges for accepting credit or debit card payments.
Why Is This Charge Being Introduced?
The introduction of MDR is aimed at creating a financially sustainable ecosystem for the companies that run India's vast digital payment infrastructure. While UPI has been revolutionary due to its free and easy-to-use nature, the banks, payment apps, and technology providers behind it incur significant costs for processing billions of transactions, maintaining security, and driving innovation. Until now, the government has provided subsidies to support the zero-MDR regime, but with transaction volumes soaring, this new fee structure is seen as a way for the ecosystem to support itself in the long run.
Are All Merchants and Transactions Affected?
No, there are important exemptions. The rule primarily impacts larger, organized merchants. All merchant transactions up to ₹2,000 are exempt from this MDR. According to ministry estimates, this covers the vast majority—around 96%—of all person-to-merchant UPI payments. Furthermore, small vendors who receive up to ₹1 lakh per month via UPI QR codes will continue to enjoy a zero-MDR benefit. There are also special, lower rates for certain essential sectors. For payments over ₹2,000, categories like railways, fuel, insurance, and telecom will incur a flat fee of just ₹5 instead of the 0.4% rate.
What Does This Mean for My Daily Payments?
For the average consumer, very little will change. Your daily chai, groceries, and other small-value purchases under ₹2,000 via UPI remain unaffected. Sending money to friends and family remains free. The key change is on the merchant's side for higher-value sales. While the rules prohibit merchants from passing the fee to customers, some in the retail industry have expressed concern that this could pressure businesses operating on thin margins, who might prefer cash for larger payments to avoid the fee. However, for now, the cost of a product or service should not change whether you pay by cash or UPI.