
Breaking Down the Numbers
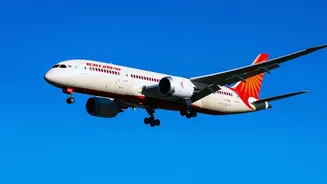
For the first half of the 2027 fiscal year, ending September 30, 2026, Air India has reported a consolidated loss. This comes despite an increase in revenue, a trend seen across the aviation industry as passenger demand remains robust. Reports citing
figures from Singapore Airlines (SIA), which holds a 25.1% stake in the airline, indicate that while a loss was recorded, it has narrowed compared to the same period in the previous year. This suggests that while the path to profitability is still a journey, there are signs of incremental financial improvement even as the airline navigates a period of intense investment and high operating costs, including elevated jet fuel prices.
The High Cost of a Rebirth
It's impossible to understand Air India's current financials without the context of its transformation. Since being reacquired by the Tata Group in 2022, the airline has embarked on Vihaan.AI, a massive five-year turnaround plan. This involves staggering capital expenditure that directly impacts short-term profitability. The company has committed over $400 million to completely refurbish its existing aircraft interiors and $200 million for a top-to-bottom IT systems overhaul. The most significant investment is a record-setting order for 470 new aircraft from Airbus and Boeing, designed to modernise the fleet, improve fuel efficiency, and enhance reliability. These foundational investments, aimed at fixing legacy issues and building a competitive product, are the primary drivers of the current losses.
Merger Mania: Integrating Vistara
Another major factor influencing the balance sheet is the ongoing merger with Vistara. Combining two full-service carriers is a complex and expensive undertaking. Initial costs include aligning employee salary structures, integrating IT and reservation platforms, and rationalising flight networks to eliminate overlap and create synergies. While the long-term goal is to create a single, more powerful full-service carrier to compete with domestic market leader IndiGo and other international giants, the short-term reality involves significant one-time integration costs. These expenses are a planned part of the transformation but contribute heavily to the bottom-line loss in the current reporting period.
Why Half-Year Results, Not a Full-Year Forecast?
The headline's focus on H1 results rather than a full-year estimate is a deliberate choice reflecting the current state of flux. For a company undergoing a radical transformation amid a volatile market, issuing long-term forecasts is fraught with risk. Factors like geopolitical instability, fluctuating fuel prices, and supply chain delays for new aircraft can render a full-year estimate obsolete almost as soon as it's announced. By reporting on a half-year basis, Air India's management can provide investors with concrete, factual performance data without speculating on variables outside their control. This approach prioritises transparency about what has happened over predictions about what might happen, which is a common strategy for companies in a deep restructuring phase.
The Path Ahead: From Investment to Profitability
The Tata Group and its partner SIA have consistently stated that the turnaround will take time. The current 'Take Off' and 'Climb' phases of the Vihaan.AI plan are focused on investment in fleet, product, and people. Profitability is a goal for the latter stages of the five-year plan. The airline is betting that these huge upfront costs will lead to greater operational efficiency, improved customer satisfaction (as measured by Net Promoter Scores, which are reportedly rising), and a stronger market position in the long run. The breakeven point is still projected to be a few years away, but the narrowing loss suggests the strategy may be heading in the right direction. The real test will be when the bulk of the investment phase is complete and the newly consolidated, modernised airline must prove it can operate efficiently and win customer loyalty in a fiercely competitive market.