



The Great Indian Savings Puzzle
For generations, Fixed Deposits (FDs) have been the bedrock of safe investing for Indian families. They offer predictable, guaranteed returns, making them a trusted tool for achieving financial goals. However, this safety comes with a trade-off. To get
the highest interest rates, you often need to lock your money away for several years. Life, however, is unpredictable. An emergency expense or a sudden opportunity might require cash, forcing you to break your FD prematurely. This not only incurs a penalty, typically between 0.5% to 1% of the interest, but also means you lose out on the potential earnings. On the other hand, letting a large sum of money sit in a regular savings account is also inefficient, as the interest earned barely keeps pace with inflation.
Enter the FD Laddering Strategy
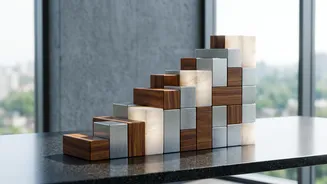
This is where a smart technique called FD laddering comes in. Instead of putting a large sum of money into a single FD, you split the amount into multiple smaller FDs with different maturity dates. This creates a 'ladder' of investments. As one FD matures, you have access to a portion of your money. If you don't need the cash, you can reinvest it to keep the ladder going. This strategy is designed to solve two problems at once: it provides regular liquidity and helps you benefit from the higher interest rates typically offered on longer-term deposits.
Building Your First FD Ladder: An Example
The concept is simpler than it sounds. Let's say you have ₹5 lakh to invest. Instead of booking a single 5-year FD, you can build a 5-rung ladder: FD 1: ₹1 lakh for 1 year FD 2: ₹1 lakh for 2 years FD 3: ₹1 lakh for 3 years FD 4: ₹1 lakh for 4 years FD 5: ₹1 lakh for 5 years At the end of the first year, your ₹1 lakh FD matures. You now have access to cash if you need it. If you don't, you can reinvest that matured amount (principal plus interest) into a new 5-year FD. The next year, your original 2-year FD matures, and you do the same. After a few years of this cycle, you will have a 5-year FD maturing every single year, giving you annual liquidity while your entire corpus benefits from long-term interest rates.
The Twin Benefits: Better Returns and Liquidity
The genius of the FD ladder lies in its dual advantages. Firstly, it enhances liquidity. Since a portion of your money becomes available at regular intervals, you are less likely to be caught off guard by an unexpected expense. This reduces the need to break a large, high-yielding FD and pay a penalty. Secondly, it helps you maximize returns. Generally, the longer the tenure of an FD, the higher the interest rate. By continuously reinvesting matured funds into longer-term FDs, you are systematically locking in better rates over time. It also helps manage interest rate risk; if rates go up, you can reinvest maturing FDs at the new, higher rate. If rates fall, a majority of your FDs are already locked in at the older, higher rates.
Is This Strategy Right for You?
FD laddering is an excellent strategy for investors who have a lump sum of money, have a low-to-moderate risk appetite, and want a disciplined approach to savings. It is particularly useful for those planning for predictable, recurring goals like annual school fees, insurance premiums, or yearly vacations. It provides the psychological comfort of knowing that cash is accessible without sacrificing the growth potential of your entire savings pool. It may require slightly more management than a single FD, as you have to track multiple maturity dates, but the benefits in flexibility and returns often outweigh this minor inconvenience for the prudent saver.