



The Old Rules No Longer Apply
For previous generations, the path was clear: secure a stable job and buy a house as soon as possible. Homeownership was synonymous with security and success. Today, the very definition of a stable career has changed. Young professionals are more likely
to switch jobs, move cities for better opportunities, or work in freelance and contract roles. This career mobility makes a 20-year home loan and a fixed address seem less like an asset and more like an anchor. The idea of being tied to one location can limit the ability to chase a promising new role in another city, a reality that is causing many to rethink the traditional homeownership dream.
Doing the New Math: EMI vs. Rent
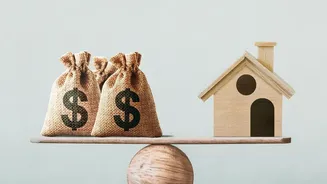
A common mistake is to directly compare a monthly home loan EMI with monthly rent. In most major Indian cities, the EMI for a mid-segment apartment is significantly higher than the rent for a similar property. For instance, a home loan of ₹60 lakh might result in an EMI of around ₹48,000, while the same apartment could be rented for ₹20,000 to ₹28,000. However, the real calculation is more nuanced. Buying involves substantial upfront costs like a 20% down payment, stamp duty, and registration fees. Renting, on the other hand, frees up that capital. This introduces the concept of 'opportunity cost'. The large sum used for a down payment could instead be invested in assets like mutual funds, which may generate significant returns over time, potentially offsetting the rent paid. It’s a shift from seeing rent as 'wasted money' to viewing it as a cost for flexibility and liquidity.
Flexibility: The Ultimate Modern Luxury
For many early-career individuals, flexibility is a more valuable asset than property. Renting allows for the freedom to easily relocate for a job, upgrade to a better home as income grows, or even move to a different neighbourhood to shorten a commute. This agility is crucial in today's dynamic job market. Furthermore, renting allows access to premium lifestyles without the long-term financial burden of ownership. Many young professionals are choosing to live in well-equipped gated communities with amenities like gyms and pools by renting, a lifestyle they might not be able to afford if they were to buy in the same location. This choice prioritises immediate quality of life and convenience over the responsibilities and financial lock-in that come with owning a property.
When Buying Still Makes Financial Sense
Despite the strong case for renting, homeownership remains a powerful tool for wealth creation and stability. The discipline of paying a monthly EMI acts as a form of forced savings, building equity in a tangible asset over time. Property appreciation, while not guaranteed, has historically been a reliable way to build long-term wealth in India, with prices in major metro areas rising steadily. Homeowners can also benefit from tax deductions on both the principal and interest components of their home loan, which can provide significant savings. For those who are certain about their long-term location and have stable income, buying a home can provide a sense of security and a hedge against inflation that renting cannot match.
A Framework for Your Decision
There is no one-size-fits-all answer. The right choice depends entirely on your personal circumstances and priorities. Before deciding, ask yourself some key questions: How long do you realistically plan to live in your current city? If the answer is less than five to seven years, the high transaction costs of buying and selling may make renting a smarter choice. What is your career trajectory? If you anticipate job changes or relocation, the flexibility of renting is invaluable. What is your financial discipline like? The argument that renters can build wealth by investing the difference only works if you are disciplined enough to actually invest that money consistently. Finally, what do you value more right now: the potential for long-term asset creation through property, or the immediate flexibility and liquidity that renting offers?