


Automate Savings First, Spend Later
The most effective strategy for guilt-free spending is to build a wall around your savings. Before you even think about upgrading your phone or planning a weekend getaway, automate your financial discipline. The principle is simple: pay your future self
first. On the day your salary hits your account, have automatic transfers set up to move a predetermined amount into your savings and investment accounts, like a Public Provident Fund (PPF) or a Systematic Investment Plan (SIP). Once that money is out of sight, the remainder of your income becomes your actual budget for the month. This simple habit reverses the common mistake of saving what's left after spending. Instead, you spend what is left after saving, ensuring your long-term goals are always the top priority. This creates a financial buffer that allows you to make lifestyle choices with confidence, not anxiety.
Adopt a Value-Based Spending Mindset
Instead of asking, "Can I afford this?" start asking, "Is this worth it to me?" This is the core of value-based spending. It isn’t about being frugal with everything; it's about spending lavishly on the things that bring you genuine joy and cutting back ruthlessly on things that don’t. Perhaps you love exploring new cuisines but don't care about having the latest smartphone. In that case, allocate a generous portion of your 'wants' budget to dining out while sticking with your current phone for another year. Track your expenses for a month to see where your money is really going. You might be surprised by how much is spent on things you barely value, like multiple unused streaming subscriptions or daily cab rides for short distances. Redirecting that money toward what truly enhances your life is the smartest upgrade you can make.
Use a Modern Budgeting Rule
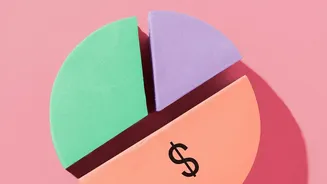
For many young professionals, the 50/30/20 rule is a game-changer. This framework suggests allocating 50% of your take-home pay to 'Needs' (rent, groceries, utilities, EMIs), 30% to 'Wants' (dining out, shopping, travel, entertainment), and 20% to 'Savings and Investments'. This structure provides a clear-cut way to balance present enjoyment with future security. The 30% for wants is your designated fund for lifestyle upgrades. Knowing you have this specific amount to spend on non-essentials helps prevent overspending and the guilt that comes with it. If you live in a high-cost metro where needs exceed 50%, you can adjust the ratio to 60/20/20, slightly reducing your 'wants' to maintain your savings discipline. Using a budgeting app can help you categorise expenses and track your progress effortlessly.
Upgrade Experiences Over Possessions
Recent trends show that young Indians increasingly prioritise experiences over material possessions. A memorable weekend trek, a workshop to learn a new skill, or a trip to a music festival often provides more lasting happiness than another gadget. Experiential upgrades also tend to be less prone to lifestyle creep. While buying a luxury car introduces recurring costs like insurance and high maintenance, a vacation is a one-time expense with lasting benefits. Before making a significant purchase, consider if an equivalent amount spent on an experience might bring more value. This shift in focus not only enriches your life but can also be a more financially sustainable way to feel like you're living better. It's about building a life rich in memories, not just assets.
Plan and Save for Big-Ticket Upgrades
Want to move to a swankier apartment or buy a premium laptop? Don't let it be an impulse decision that wipes out your savings. Treat major lifestyle upgrades like any other financial goal. Create a dedicated sinking fund—a separate savings pot—for that specific purpose. Calculate the total cost and divide it by the number of months you're willing to wait. Then, set aside that smaller, manageable amount each month. For example, instead of draining ₹90,000 from your emergency fund for a new gadget, saving ₹10,000 a month for nine months makes the purchase feel earned and financially sound. This planned approach prevents large expenses from derailing your primary savings goals and helps you distinguish between a fleeting desire and a genuine, long-term want.