


The Big Question: Will You Pay for UPI?
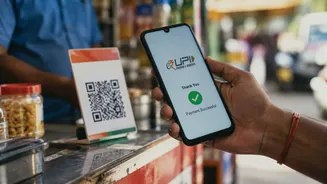
Let's clear the air: for you, the consumer, UPI remains free for everyday use. The government and the National Payments Corporation of India (NPCI) have been firm on this. You will not be charged for sending money to friends or family (person-to-person
or P2P), regardless of the amount. Similarly, paying a merchant for goods or services up to ₹2,000 will continue to have no extra cost for you. The new rules taking effect on October 15, 2026, are not aimed at charging customers.
So What's Changing? Understanding MDR
The change is the introduction of a Merchant Discount Rate (MDR) for certain transactions. An MDR is a fee that merchants pay to payment service providers (like banks and fintech apps) for processing digital payments. From October 15, 2026, a 0.4% MDR will apply to person-to-merchant (P2M) UPI payments above ₹2,000. For very large transactions of ₹75,000 or more, this fee is capped at a maximum of ₹300. It is crucial to understand that this is a charge levied on the merchant, not the customer. Official guidelines explicitly prohibit merchants from passing this cost on to you.
Why Introduce Fees Now?
Running the massive UPI infrastructure isn't free. Banks, the NPCI, and payment apps incur significant costs for technology, server maintenance, and fraud prevention, estimated at around ₹20,000 crore annually. For years, the government provided subsidies to cover these costs and encourage digital adoption. However, with transaction volumes soaring, these subsidies are no longer seen as a sustainable long-term solution. The introduction of a structured, threshold-based MDR is designed to create a self-sustaining financial model for the payments ecosystem, ensuring its continued reliability and innovation without relying solely on government funds.
Who Does This Affect Most?
This policy primarily affects medium to large businesses that process high-value UPI transactions. According to government estimates, about 96% of all merchant transactions will remain unaffected by the MDR, as they are either below the ₹2,000 threshold or fall under exemptions. Small merchants, such as local vendors who receive up to ₹1 lakh per month via UPI QR codes, will continue to enjoy a zero-MDR framework. However, some larger merchants have expressed concern. A recent survey by LocalCircles found that 83% of merchants are unwilling to absorb the new fee. This has raised worries that some businesses might try to pass the cost to consumers, despite it being against the rules, or encourage cash payments for larger purchases.
What About Special Cases?
The framework includes different rates for specific sectors. For instance, payments for essentials like fuel, insurance, railways, and telecom will attract a lower, flat MDR of ₹5 for transactions over ₹2,000, rather than the 0.4% rate. Furthermore, automated payments like monthly subscriptions (UPI AutoPay), SIPs, and other recurring mandates are completely excluded from this new MDR, meaning they remain free regardless of the amount. The distinction also matters between payments from a bank account versus a PPI wallet. The new 0.4% MDR applies to bank account-to-merchant payments, while wallet-based UPI payments have a separate interchange fee structure that has been in place for some time.