



The Savings Account: Your Financial Bedrock
Your savings account is the foundation of your financial life. It's liquid, meaning you can access your money anytime, making it perfect for daily expenses and a crucial emergency fund. However, its biggest strength is also its weakness for growth. With
interest rates typically struggling to keep pace with inflation, the money in your savings account is safe but isn't actively growing. Think of it as a waiting room for your money—excellent for short-term needs and safety, but not a place for long-term wealth creation.
The Next Step Up: Fixed and Recurring Deposits
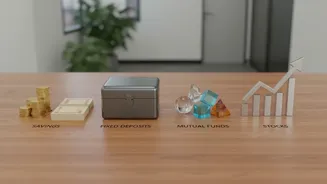
Fixed Deposits (FDs) and Recurring Deposits (RDs) are traditional favourites for a reason. They offer higher interest rates than savings accounts with virtually no risk to your principal amount. An FD involves depositing a lump sum for a fixed period, while an RD allows you to deposit a fixed amount every month. These are excellent for short-to-medium-term goals, like saving for a down payment or a vacation. The trade-off is liquidity; withdrawing your money before the tenure ends often incurs a penalty. While safer than market-linked options, their returns may still only just beat inflation.
Entering the Market: Mutual Funds and SIPs
For many young Indians, mutual funds are the gateway to market-linked investments. A mutual fund pools money from many investors to invest in a diversified portfolio of stocks, bonds, or other assets. This diversification helps to spread out risk. The easiest way to start is through a Systematic Investment Plan (SIP), which allows you to invest a small, fixed amount regularly. This builds discipline and averages out your purchase cost over time. Mutual funds come in various types—equity funds for higher growth potential, debt funds for stability, and hybrid funds for a balance. While they offer the potential for much higher returns than FDs, they are subject to market risks and do not guarantee returns.
High Risk, High Reward: Direct Stocks
Investing directly in the stock market means buying shares of individual companies. This option offers the highest potential for growth but also comes with the highest risk. If the companies you invest in do well, your returns can be substantial. However, if they perform poorly, you could lose a significant portion of your investment. Unlike mutual funds which are managed by a professional fund manager, direct stock investing requires you to do your own research and constantly monitor the market. It is generally advised for those who have a good understanding of the market and a higher risk tolerance.
First, Know Yourself: Risk, Goals, and Time
Before choosing any product, the most important step is to understand your own financial personality. This is often called risk profiling. Ask yourself three key questions. First, what is your risk tolerance—how comfortable are you with the possibility of losing money for the chance of higher returns? Second, what are your financial goals—are you saving for a short-term goal like a phone or a long-term one like retirement? Third, what is your investment horizon—how long can you leave your money invested? A young person investing for retirement 30 years away can afford to take more risks than someone saving for a wedding next year. Answering these questions will guide you to the right mix of products.