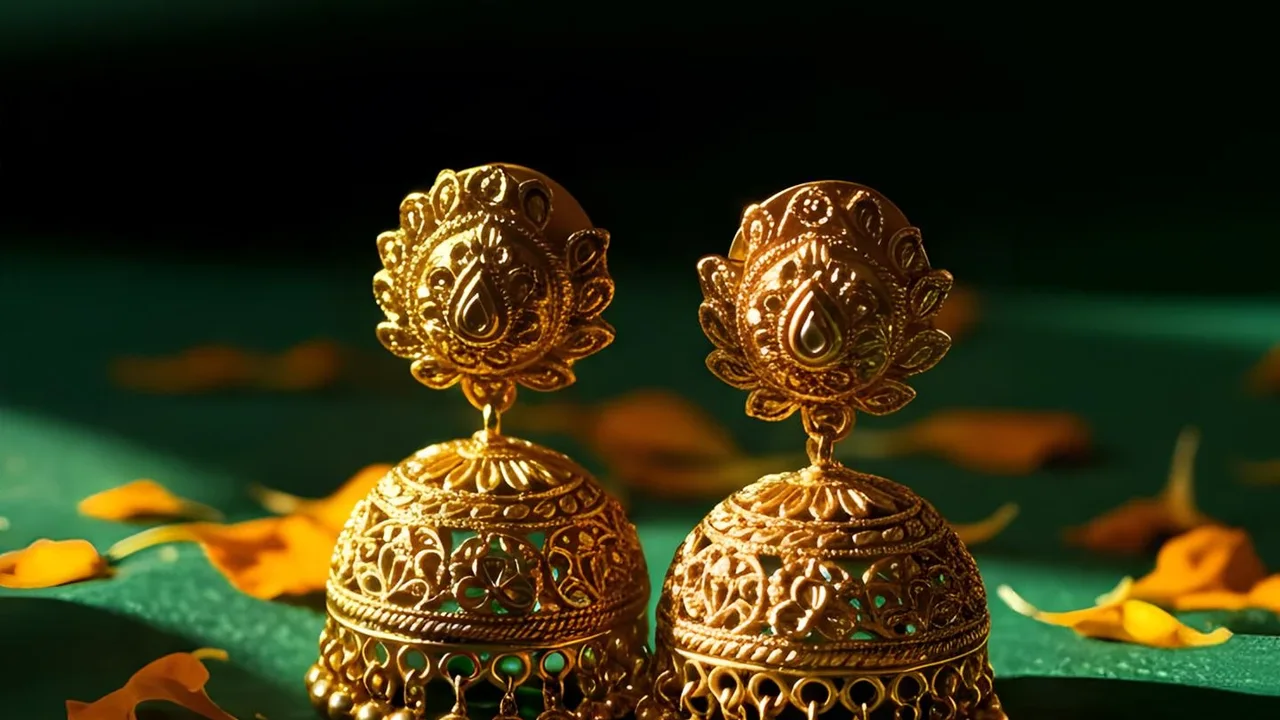


In India, gold is more than an asset; it's a source of swift financial relief. Pledging gold jewellery for a loan is a common way to unlock quick funds, but not all loan offers are created equal. Here's how to compare them effectively.
How Pledged Gold Security Works
A gold loan is a secured
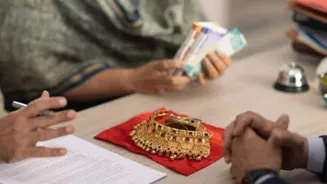
loan where you hand over your gold ornaments to a lender as collateral. The lender assesses the purity and weight of the gold to determine its market value. Based on this value, they offer you a loan amount. Your gold is stored securely in a vault and is returned to you once the loan, along with the interest, is fully repaid. This process is typically much faster than unsecured loans because the physical asset reduces the lender's risk, and it often doesn't require income proof or a strong credit history.
Key Factors for a Smart Comparison
Looking beyond the advertised interest rate is crucial. The best deal depends on a combination of factors. The interest rate is the primary cost, with rates from major banks and Non-Banking Financial Companies (NBFCs) typically starting from around 8.5% to 12% per annum, but can go higher depending on the scheme. Another critical factor is the Loan-to-Value (LTV) ratio, which is the percentage of your gold's value that a lender will provide as a loan. The Reserve Bank of India (RBI) generally caps the LTV at 75%, meaning for gold worth ₹1 lakh, you can get a loan of up to ₹75,000. Some lenders may offer higher LTVs for smaller loan amounts under specific schemes. Finally, always ask about processing fees, which can be a percentage of the loan amount (0.25% to 2%), and other potential costs like valuation charges, documentation fees, and prepayment penalties.
Banks vs. NBFCs: Which Is Better for You?
Your choice between a bank and an NBFC depends on your priorities: speed, cost, or flexibility. Banks, especially public sector banks, often offer lower interest rates, typically in the 8-12% range, due to their lower cost of funds. They are also perceived as highly secure for storing your pledged jewellery. However, the loan approval process at a bank can be slower, sometimes taking a few days due to stricter documentation and eligibility checks. On the other hand, NBFCs like Muthoot Finance and Manappuram Finance are known for their speed and convenience, often disbursing loans within a few hours with minimal paperwork. This convenience may come at the cost of slightly higher interest rates, which can sometimes exceed 12%. NBFCs might also offer more flexible repayment options and are often more willing to provide smaller loan amounts.
The Application and Pledging Process
The process of getting a gold loan is relatively simple. It begins with you taking your gold jewellery to a lender's branch, though some now offer online applications and doorstep services. A certified appraiser will then evaluate your gold's weight and purity (usually for 18 to 24-karat gold) in your presence. You will need to provide basic KYC documents, including proof of identity (like an Aadhaar or PAN card) and proof of address. Once the valuation and documents are verified, the lender presents a loan offer. If you accept the terms, you sign the loan agreement, and the funds are disbursed to your bank account, often instantly.
Avoiding Common Pitfalls
While gold loans are convenient, there are potential traps to be aware of. The most significant are hidden charges that go beyond the interest rate. Always request a full schedule of fees, including processing, valuation, and potential late payment or foreclosure penalties, before signing. Some lenders charge a penalty of up to 2% for repaying the loan early. Also, be mindful of the repayment schedule. Missing payments can attract high penal interest, which is charged on top of your regular interest rate. Finally, if you fail to repay the loan, the lender has the right to auction your gold after giving you notice, so it's vital to understand the lender's auction policy.