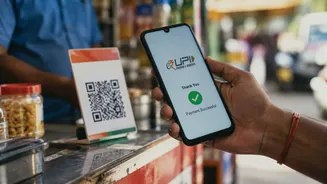




Confusion around new UPI charges has been rampant. With the October 15 deadline approaching, it's crucial to understand what's changing. The good news? For most users and most transactions, India's favourite payment method remains completely free.
The Core Rule: What Changes on October 15?
Starting
October 15, 2026, a new framework called the Merchant Discount Rate (MDR) will apply to some Unified Payments Interface (UPI) transactions. Specifically, a charge of 0.4% will be levied on payments above ₹2,000 made to eligible merchants. For very large transactions of ₹75,000 or more, this fee is capped at a maximum of ₹300. It's important to understand that this is not a blanket charge on all UPI payments. Person-to-person (P2P) transfers, like sending money to a friend or family member, remain completely free, regardless of the amount. Additionally, all UPI merchant payments up to ₹2,000 are also exempt from this new charge.
Who Actually Pays This Fee?
This is the most crucial point of clarification: customers do not pay this fee. The 0.4% MDR is a charge that the merchant's bank collects from the merchant for processing the digital payment. The government and the National Payments Corporation of India (NPCI) have been firm that merchants are not allowed to pass this cost on to the consumer by adding a surcharge to the bill. So, if you buy an item for ₹3,000 and pay via UPI, you will only pay ₹3,000. The merchant will receive that amount minus the applicable MDR of ₹12. The Ministry of Finance has assured that it will monitor merchants to ensure this rule is followed.
Bank vs. Wallet: An Important Distinction
The new MDR framework primarily applies to standard UPI transactions made from a linked bank account. It is, however, distinct from a separate rule that has been in place since April 2023 for payments made via a Prepaid Payment Instrument (PPI), such as a digital wallet. For those transactions, an interchange fee of up to 1.1% can apply to merchant payments over ₹2,000. This interchange fee is a charge settled between the payment providers and is also not directly paid by the customer. For over 99.9% of users who make UPI payments directly from their bank account, the new 0.4% MDR is the relevant rule to understand, and even then, the cost is not borne by them.
What Stays Completely Free for Everyone?
Let's be clear about what is not changing. The vast majority of UPI transactions will continue to be free for both customers and merchants. This includes: - All person-to-person (P2P) money transfers of any amount. - All person-to-merchant (P2M) payments up to ₹2,000. - Payments made to small merchants who are part of the P2PM framework and receive up to ₹1 lakh per month via UPI. - Recurring payments set up through UPI AutoPay, such as for subscriptions or bills, regardless of the amount. Given that an estimated 95-96% of all UPI merchant transactions are below the ₹2,000 threshold, most daily payments remain entirely unaffected by the new MDR.
Why Was This Fee Introduced?
For years, UPI has operated on a zero-MDR model to encourage widespread adoption. However, running and maintaining the massive infrastructure that processes over 2,400 crore transactions a month has significant costs related to server capacity, cybersecurity, and fraud prevention. Previous government subsidies proved insufficient to cover these growing expenses. The introduction of a nominal MDR on higher-value merchant transactions is intended to create a self-sustaining financial model for the UPI ecosystem. This ensures that banks and payment service providers can continue to invest in the technology, keeping it secure and innovative for the long term without charging end users.