





The Old Rules No Longer Apply
For generations, the advice was simple: buying a home is a cornerstone of financial stability, and renting is just “throwing money away.” Owning property was seen as a forced savings plan and a guaranteed path to building wealth. Every EMI payment was a step
towards owning a tangible asset that would appreciate over time. This wisdom was rooted in an era of stable, long-term careers and more predictable housing markets. But in 2026, the ground beneath our feet has shifted. The traditional logic is being challenged by a new economic reality where affordability is stretched and career paths are no longer linear.
The Affordability Squeeze is Real
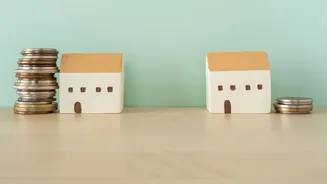
Property prices in India's major cities have climbed significantly. In cities like Bengaluru, a 2BHK apartment can now cost between ₹1 to ₹1.5 crore, while in Mumbai, similar properties are priced even higher. This surge has outpaced income growth for many, making the initial down payment—typically 20% of the property’s value—a formidable barrier. Even with home loan interest rates stabilising, the EMI for a mid-segment apartment is often substantially higher than the rent for a comparable unit. This widening gap between rent and EMIs forces a difficult choice: stretch your finances for an asset, or rent comfortably and invest the surplus elsewhere? The math increasingly suggests that unless you plan to stay put for over five to seven years, buying might not be the automatic financial win it once was.
Your Career is More Flexible, and So is Your Address
The rise of remote and hybrid work is fundamentally rewiring the housing decision. Proximity to the office is no longer the absolute priority it once was. This newfound flexibility allows professionals to consider living in suburban areas or even Tier-2 cities, where they can get larger homes and a better quality of life for a lower cost. Renting perfectly complements this modern, nomadic career path. It offers the freedom to relocate for a new job, move to a different city to be closer to family, or simply explore a new neighbourhood without the heavy financial and logistical burden of selling a property. In this context, renting isn't a compromise; it's a strategic choice that values mobility and adaptability in a dynamic job market.
Rethinking 'Wasted Money'
The argument that rent is wasted money ignores what you get in return: flexibility, convenience, and zero maintenance liability. When you rent, major repairs, society charges, and property taxes are the landlord's headache. You pay a fixed amount for a place to live, and the rest of your income is free for other goals. In contrast, the true cost of homeownership goes far beyond the EMI. There are stamp duty and registration fees (5-8% of the property value), interior and furnishing costs, brokerage fees, and ongoing expenses like property taxes and maintenance charges. These hidden costs can add up to 15-25% over the base price of the property, a significant financial burden that the simple EMI vs. rent comparison overlooks.
A New Framework for Your Decision
Instead of seeking a universal answer, the modern rent-versus-buy debate requires a personal one. The right choice depends entirely on your individual circumstances. Ask yourself: How stable is my income and career path? Do I plan to stay in this city for the next seven years or more? Do I have the discipline to invest the money I save by renting, or do I need the forced savings of an EMI? For some, especially in cities with a high price-to-rent ratio like Mumbai, renting and diligently investing the difference in assets like mutual funds could generate more wealth over time. For others who crave stability and are confident in their long-term location, the emotional security and wealth-building potential of owning a home remain unparalleled.