
The Case for Flexibility
For many young Indians in their 20s and early 30s, a career path is no longer linear or confined to one city. Renting offers unparalleled mobility to seize a better job opportunity in another state or even abroad without the burden of selling a property.
This freedom from a long-term commitment is a significant advantage in a dynamic job market. Unlike buying, renting involves a lower upfront cost, typically a security deposit of a few months' rent, rather than a substantial down payment. This preserves liquidity, allowing young professionals to keep their savings accessible for other investments, emergencies, or life experiences. Furthermore, rental agreements often place the responsibility for major repairs and maintenance on the landlord, providing predictable monthly expenses.
The Financial Realities of Buying
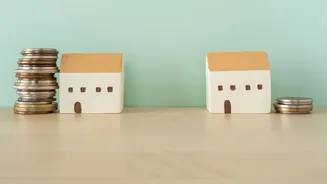
Buying a home is often positioned as the most significant investment one can make. While it offers emotional security and builds a tangible asset, the financial entry barrier is high. A home purchase requires a down payment, typically 20% of the property's value, which can be a substantial sum for those early in their careers. Beyond the listed price, there are numerous other expenses that can significantly inflate the total cost. These include stamp duty and registration fees, which can amount to 5-10% of the property value, home loan processing fees, property taxes, and ongoing maintenance charges. In many new residential projects, costs for parking, preferential location, and even basic interior work are charged separately, adding lakhs to the final bill.
Is Rent Really 'Wasted Money'?
The traditional argument against renting is that it’s like “throwing money down the drain.” However, a closer look at the numbers challenges this notion. In the initial years of a home loan, a large portion of the Equated Monthly Instalment (EMI) goes towards paying off interest, not building equity. For example, on a 20-year loan, interest can constitute over 80% of payments in the first year. Financial experts argue that the more accurate comparison is between rent and the non-recoverable costs of ownership, such as interest, property taxes, and maintenance. If the difference between the EMI and rent, plus the initial down payment, is consistently invested in assets like mutual funds, a renter could potentially build a larger financial corpus over time than a homeowner, depending on market performance.
Making the Right Choice for You
Ultimately, there is no one-size-fits-all answer. The decision to rent or buy hinges on individual circumstances, career stability, and long-term goals. Buying makes more sense for those who plan to stay in one city for a longer period, typically more than seven years, allowing time for the property's value to appreciate and offset the high initial transaction costs. It offers stability and tax benefits on home loan repayments. Renting is better suited for those who prioritise career flexibility, want to avoid the financial strain of a large loan, and prefer to maintain liquidity for other investment opportunities. The key is to move beyond the emotional appeal and assess the decision with a clear-eyed view of the numbers and your personal life stage.