
The Big Change: It's About Charges, Not Your Payments
Recent headlines about new UPI charges have caused some confusion among investors. The core update, effective October 15, 2026, introduces a Merchant Discount Rate (MDR) on certain UPI transactions over ₹2,000. However, for most mutual fund investors,
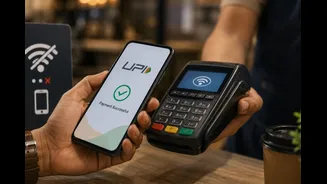
the good news is that this change will likely not affect your regular investments. The National Payments Corporation of India (NPCI) has explicitly clarified that recurring payments made through UPI AutoPay for Systematic Investment Plans (SIPs) are exempt from these new MDR charges. This means if you have an automated monthly SIP set up via UPI, it will continue to be processed without any additional fee being levied on the transaction.
AutoPay vs. One-Time Payments: A Key Distinction
The new rules draw a clear line between automated recurring payments and one-time manual transactions. Your SIP, which runs on a pre-authorised UPI AutoPay mandate, is considered a recurring payment and remains unaffected. However, if you make a fresh, one-time lump sum investment into a mutual fund using UPI, it may be subject to a different, much lower MDR. The framework specifies a concessional MDR of just 0.02% for capital market transactions, which includes payments to mutual funds and brokers, and this is capped at a maximum of ₹300 per transaction. The crucial point is that this MDR is a charge within the merchant ecosystem and is not supposed to be passed on to you, the customer.
Why Were These Rules Introduced?
The introduction of an MDR framework is aimed at creating a sustainable financial model for the UPI ecosystem. As UPI has grown exponentially, the costs associated with maintaining its vast infrastructure, ensuring cybersecurity, and providing customer service have also increased. By introducing a nominal MDR on specific high-value merchant transactions, the ecosystem can generate revenue to support its operations and continued innovation. The government and NPCI have been careful to protect consumers and the most common use cases. By exempting personal transfers, small-value transactions, and recurring payments like SIPs, they ensure that UPI remains a free and convenient tool for the vast majority of users and their everyday financial habits.
Enhanced Security: The Other 'New Rule' You Must Know
Beyond the MDR framework, another significant rule change from the Securities and Exchange Board of India (SEBI) focuses on enhancing investor security for all UPI payments to brokers and mutual funds. To combat fraud, SEBI has mandated that all registered intermediaries must use special, validated UPI IDs. These official handles will now include the suffix '@valid' in their UPI ID (e.g., 'fundname.mf@validbankname'). When you make a payment to such a verified ID, your UPI app should display a green thumbs-up icon, visually confirming that the recipient is a legitimate, SEBI-registered entity. This makes it much harder for fraudulent accounts to impersonate genuine investment platforms.
What Should Investors Do Now?
For your existing UPI AutoPay SIPs, no immediate action is required. They will continue as before, without the new MDR charges. However, you must be vigilant about the new security rules. For any new investment, whether a lump sum payment or setting up a new SIP, always double-check for the '@valid' UPI handle and the green thumbs-up icon in your payment app before authorising the transaction. SEBI has also introduced a verification tool called 'SEBI Check' on its website, allowing you to confirm the authenticity of an intermediary’s UPI ID or bank account details before sending money. Adopting these safety checks is now a critical part of investing responsibly in the digital age.