




What Exactly Is FD Laddering?
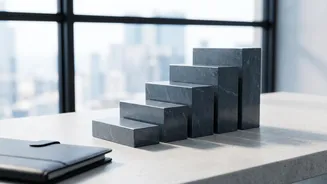
Fixed deposit laddering is an investment strategy where you divide a lump sum of money into several smaller fixed deposits with different maturity dates, instead of investing it all in a single FD. Imagine you have ₹5 lakh to invest. Instead of locking
it all away for five years, you could split it into five FDs of ₹1 lakh each. The first matures in one year, the second in two years, the third in three, and so on. This creates a 'ladder' of investments, with each rung representing a deposit that will mature at a different time. This structure is designed to provide greater flexibility and liquidity than a single, long-term deposit.
The Core Benefits: Liquidity and Better Returns
The primary advantage of FD laddering is enhanced liquidity. Since a portion of your investment matures at regular intervals—every year, in our example—you have access to cash without needing to break a larger deposit and incur a penalty. This predictable cash flow can be aligned with future expenses. The second key benefit is the potential for optimised returns. The strategy helps average out interest rate risk. If rates rise, you can reinvest your maturing FDs at the new, higher rate. If rates fall, only a portion of your portfolio is affected, as the rest remains locked in at the older, higher rates. This approach avoids the risk of committing all your funds at a single, potentially unfavourable interest rate.
How to Build Your FD Ladder: A Step-by-Step Guide
Creating an effective FD ladder requires a bit of planning. First, determine the total amount you want to invest. Next, divide this corpus into smaller, equal parts. For example, a ₹10 lakh corpus could be split into five FDs of ₹2 lakh each. Then, assign different tenures to each deposit to stagger their maturity dates. A common approach is to set them to mature one year after another—in one, two, three, four, and five years. As the first FD (the one-year deposit) matures, you have a choice: use the funds if needed, or reinvest the principal and interest into a new five-year FD. By reinvesting the matured amount for the longest tenure in your ladder, you create a rolling system where an FD matures every year, giving you both liquidity and the benefit of higher long-term interest rates.
Advanced Considerations for Mastery
To truly master this strategy, consider a few more factors. First, diversify across different banks to mitigate risk, especially if your total investment exceeds the deposit insurance limit. Second, keep an eye on the interest rate cycle. If rates are expected to rise, you might want to keep your initial tenures shorter to reinvest sooner at higher rates. Conversely, in a falling rate environment, locking in longer tenures can be advantageous. Finally, remember the tax implications. Interest earned from FDs is added to your total income and taxed according to your applicable slab rate. Banks will deduct Tax at Source (TDS) if your annual interest income from that bank exceeds ₹40,000 (or ₹50,000 for senior citizens). This happens on an accrual basis, meaning tax is applicable each year, even on cumulative FDs where you don't receive the interest payout.
Potential Downsides to Keep in Mind
While effective, FD laddering is not without its drawbacks. The returns, while stable, will likely be lower than those from market-linked instruments like equities or mutual funds. The strategy also requires active management; you need to track maturing deposits and decide whether to reinvest or withdraw, otherwise funds could sit idle. Furthermore, in a persistently falling interest rate environment, your overall returns may diminish as you reinvest maturing FDs at progressively lower rates. It is also important to consider that the real return on your investment may be impacted by inflation, which can erode the purchasing power of your money over time.