




The Big Announcement: A Rate Hike
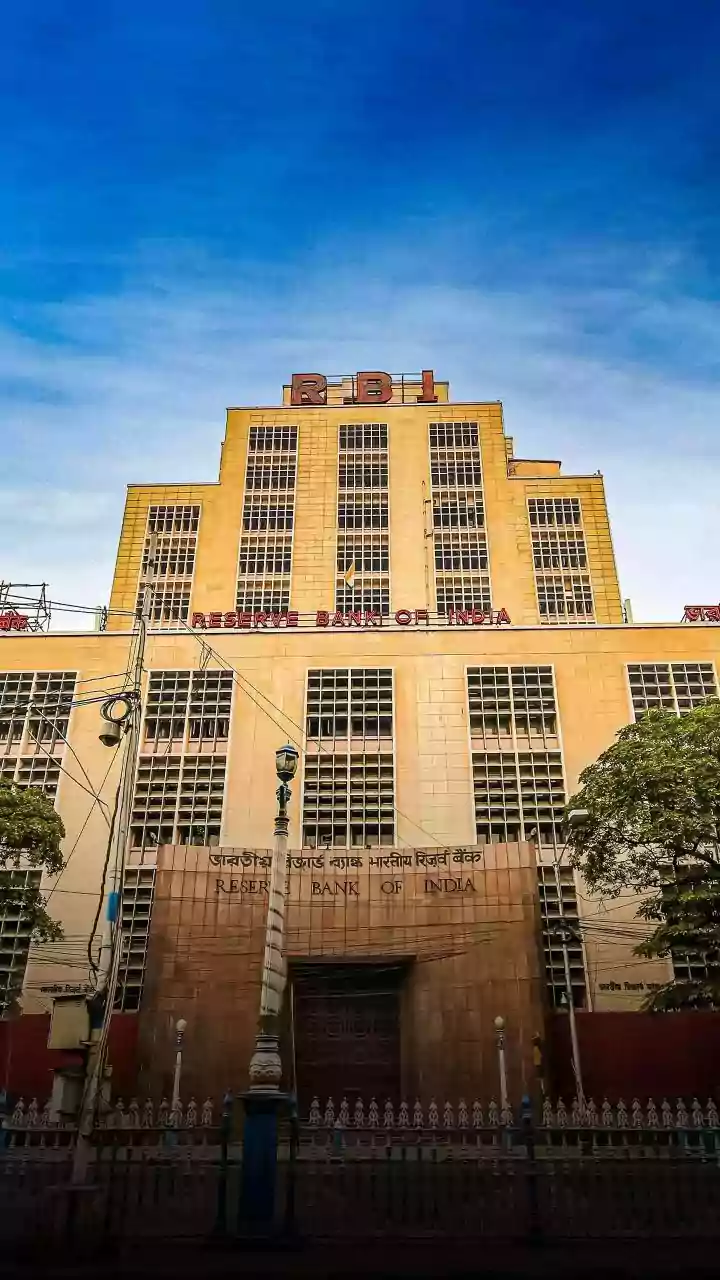
On October 7, 2026, the RBI's Monetary Policy Committee (MPC) announced a significant decision: it increased the repo rate by 25 basis points, moving it from 5.25% to 5.50%. Simply put, the repo rate is the interest rate at which the central bank lends
money to commercial banks. When this rate goes up, the cost of funds for banks increases, and they typically pass this on to customers through higher interest rates on loans, including home, auto, and personal loans. This is the first time the RBI has hiked the rate since February 2023, marking a clear shift in its policy direction. The MPC also changed its policy stance from 'neutral' to 'calibrated tightening', signalling that future rate cuts are off the table for now and more hikes could follow if needed.
Why Now? Taming Stubborn Inflation
The primary driver behind this rate hike is the RBI's renewed focus on controlling inflation. Governor Sanjay Malhotra highlighted that price pressures have become more persistent and widespread. The central bank has raised its inflation forecast for the financial year 2026-27 to 5.2%, which is above its 4% target. Several factors are contributing to this, including rising global crude oil prices, a weak monsoon which could affect food prices, and general supply-side risks. At the same time, the Indian economy is showing strong resilience. The RBI actually upgraded its GDP growth forecast for the year to 7.1%. This strong growth gives the central bank the confidence to tighten monetary policy to fight inflation without fearing a major economic slowdown.
Impact on Your Existing EMIs
If you have an existing loan, the impact depends on your interest rate type. For those with floating-rate loans, particularly home loans linked to an external benchmark like the repo rate, an EMI increase is imminent. Once your bank adjusts its lending rate to reflect the new repo rate, your monthly payment will go up, or your loan tenure might be extended. For example, on a Rs 50 lakh home loan with a 25-year tenure, a 0.25% rate increase could push your monthly EMI up by approximately Rs 817. Borrowers who took out large loans during the recent low-interest period will feel this pinch most acutely. However, if you have a fixed-rate loan, your EMI will remain unchanged until your fixed-rate period ends.
Planning a New Loan? Here's the New Reality
For anyone planning to take out a new home, auto, or personal loan, the era of progressively cheaper credit is over. New borrowers will now face higher interest rates from the outset compared to just a few months ago. Banks had already started increasing their spreads (the margin over the repo rate) even before this hike. This policy shift solidifies a 'higher for longer' rate environment. It means households must now approach new debt with more caution. Thoroughly compare offers from different lenders, as their final rates can vary significantly. It’s also crucial to reassess your budget to ensure you can comfortably manage higher EMIs, as economists suggest there's a possibility of further rate hikes before the end of the financial year.