


What Exactly Is FD Laddering?
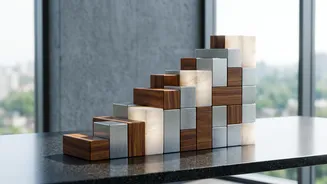
Fixed Deposit laddering is an investment technique where you divide a lump sum of money into multiple FDs with different maturity dates instead of investing the entire amount in a single FD. For instance, instead of putting ₹5 lakh into one five-year
FD, you could split it into five FDs of ₹1 lakh each, with tenures of one, two, three, four, and five years. This creates a 'ladder' where one FD matures each year, giving you a regular flow of funds while the rest of your money continues to earn interest.
The Twin Benefits: Better Liquidity and Optimised Returns
The primary advantage of laddering is enhanced liquidity. Since a portion of your investment matures at regular intervals, you have access to cash for planned expenses or emergencies without having to break a larger deposit and incur a penalty. The second key benefit is mitigating interest rate risk. If you lock all your money into a single long-term FD and interest rates go up, you lose out. With a ladder, as each FD matures, you can reinvest it at the prevailing, potentially higher, rate. This helps in averaging out your interest earnings over time and optimising overall returns.
Step 1: Assess Your Funds and Goals
Before building your ladder, determine the total amount you want to invest. This should be money you can afford to lock away for at least a year. Next, define your financial goals. Are you saving for a down payment, a child's education, or creating a steady income stream for retirement? Your goals will influence the structure of your ladder, such as how many FDs (or 'rungs') you need and the duration of their tenures.
Step 2: Split Your Corpus and Stagger the Tenures
Once you have your total investment amount, divide it across the number of FDs you plan to create. For simplicity, many investors split the amount equally. For example, a ₹10 lakh corpus can be split into five FDs of ₹2 lakh each. Then, assign a different tenure to each FD to create the staggered maturity dates. A common structure is to have deposits maturing in one, two, three, four, and five years. This ensures that starting from the end of the first year, you have one FD maturing annually.
Step 3: Reinvest and Maintain the Ladder
The strategy's power comes from consistency. As each FD matures, you have a choice: use the funds if needed or reinvest them to maintain the ladder. To maximise growth, the standard practice is to reinvest the matured principal and interest into a new FD with the longest tenure in your ladder. For example, when your one-year FD matures, you reinvest it for a five-year term. After a few years, your entire ladder will consist of long-tenure FDs (which typically offer higher interest rates), but one will still mature every year.
Things to Keep in Mind
While effective, laddering isn't a magic bullet for the highest possible returns. If interest rates fall, you will have to renew your maturing FDs at lower rates. Also, managing multiple FDs requires more tracking than a single deposit. It's also wise to diversify your FDs across different banks to mitigate institutional risk. Finally, remember that interest earned from FDs is taxable according to your income tax slab, and splitting deposits does not change this liability.