





What is Fixed Deposit Laddering?
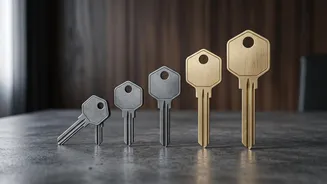
Fixed Deposit (FD) laddering is a simple yet powerful strategy where you split a lump-sum investment into multiple FDs with different maturity dates instead of putting it all in a single deposit. Think of it as building a ladder with several rungs. Each
FD is a rung, and because they mature at different times, you always have a 'rung' within reach. This staggered approach ensures that a portion of your money becomes available at regular intervals, such as every few months or once a year.
How the Laddering Strategy Works
Imagine you have ₹5 lakh to invest. Instead of booking a single ₹5 lakh FD for five years, you could build a five-rung ladder. You would split the amount into five FDs of ₹1 lakh each. You invest the first lakh for one year, the second for two years, the third for three years, and so on, up to five years. At the end of the first year, your first FD matures. If you don't need the cash, you can reinvest that ₹1 lakh into a new five-year FD. When the second year ends, your original two-year FD matures, and you can reinvest that for another five years. By repeating this process, you eventually have a portfolio where one FD matures every single year, giving you access to funds while the rest of your money continues to earn higher interest typical of longer-term deposits.
Benefit 1: Maximizing Your Interest Earnings
Longer-term FDs generally offer higher interest rates than short-term ones. A single, short-term FD for liquidity would mean sacrificing returns. The laddering strategy allows you to benefit from those higher long-term rates. As each short-term FD on your initial ladder matures, you reinvest it for a longer duration (e.g., five years). Over time, your entire portfolio consists of long-term FDs, systematically boosting your overall interest earnings.
Benefit 2: Ensuring Liquidity for Emergencies
The core advantage of laddering is that it provides regular access to your money. If an unexpected expense arises, instead of prematurely breaking a large, long-term FD and paying a penalty, you can simply use the funds from the next deposit that is scheduled to mature. This structure gives you predictable cash flow. You know exactly when a portion of your savings will be available, allowing for better financial planning for everything from emergencies to planned expenses.
Benefit 3: Reducing Interest Rate Risk
Interest rates fluctuate. If you lock all your money into a single FD, you risk committing to a low rate for a long period, especially if rates rise later. Laddering mitigates this risk. Since your FDs mature at different times, you are reinvesting smaller amounts periodically. If interest rates have gone up, you can take advantage of the higher rates with the maturing amount. If rates have fallen, only one portion of your money is reinvested at the lower rate, while your other FDs continue to earn at the older, higher rates until they mature. This effectively averages out your returns over time.
Steps to Build Your Own FD Ladder
Building your own FD ladder is straightforward. First, decide on the total amount you wish to invest. Second, determine how many FDs (or 'rungs') you want in your ladder; three to five is a common and manageable number. Third, divide your total investment equally among the FDs. Finally, open the FDs with staggered tenures—for instance, 1 year, 2 years, 3 years, and so on. As each one matures, decide if you need the funds or if you can reinvest it into a new FD at the longest tenure of your ladder to keep the system going.