

Your Emergency Fund: The Financial Safety Net
Think of an emergency fund as your personal financial firefighter. Its sole job is to be ready for unexpected crises that require immediate cash. These aren't planned expenses like a vacation; they are genuine emergencies such as a sudden job loss, an urgent
medical bill, or a critical home repair. The primary characteristic of this fund is liquidity, meaning the money must be easily and quickly accessible without penalty or loss. For this reason, emergency funds are typically kept in high-yield savings accounts or money market accounts, where the money is safe from market fluctuations. The goal isn't to grow wealth with this money but to preserve it and ensure it's there when you need it most, preventing you from falling into high-interest debt or being forced to sell other assets at a bad time.
Long-Term Investments: The Engine for Growth
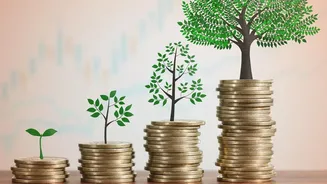
If an emergency fund is your safety net, long-term investments are your engine for building wealth. The purpose here is completely different: to grow your money over an extended period, typically five years or more. This is the money you use to achieve major life goals, like funding your retirement, buying a home, or paying for a child's education. Unlike an emergency fund, this money is put to work in assets like stocks, bonds, mutual funds, and real estate, which have the potential for significant growth. This growth is largely powered by the principle of compounding, where your returns start earning their own returns, accelerating your wealth creation over time. However, this potential for higher returns comes with higher risk; the value of these assets can and will fluctuate with the market.
Key Difference 1: Purpose and Time Horizon
The most fundamental difference lies in their purpose. An emergency fund is for short-term survival; it’s a defensive tool designed to protect you from immediate financial shocks. Its time horizon is 'now'. In contrast, long-term investments are for future thriving; they are an offensive tool designed to build your net worth over years and decades. Their time horizon is 'later'. Confusing these two can be disastrous. Using investment funds for an emergency might mean selling assets at a loss during a market downturn, permanently damaging your long-term goals. Conversely, keeping too much cash in an emergency fund means you miss out on the growth needed to beat inflation and build real wealth.
Key Difference 2: Liquidity vs. Growth
This boils down to a classic financial trade-off: liquidity versus growth. An emergency fund prioritises liquidity above all else. You need to be able to convert it to cash instantly without losing a single rupee of the principal. This is why it's kept in safe, easily accessible accounts that offer very modest returns. Long-term investments, on the other hand, prioritise growth. You intentionally give up immediate access to that money in exchange for the potential of higher returns. Withdrawing from investment accounts can take days and may come with tax implications or penalties, making them unsuitable for urgent needs.
How They Work Together for Financial Health
An emergency fund and long-term investments are not competing against each other; they are two essential parts of a single, robust financial plan. Financial experts typically recommend saving three to six months' worth of essential living expenses in your emergency fund first. Once that safety net is in place, you can start investing more aggressively for the long term. The emergency fund acts as a protective wall around your investments. When an unexpected expense arises, you can pull from your liquid emergency savings without derailing your investment strategy. This prevents panic-selling and allows your investments to continue growing, undisturbed by life's short-term dramas.