



The Engine of Growth: Understanding Compounding
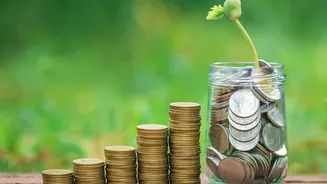
At its heart, compounding is the process where your investment returns begin to generate their own returns. It’s like a snowball rolling downhill, picking up more snow and growing at an accelerating rate. If you invest ₹10,000 and earn a 7% return in the first
year, you now have ₹10,700. The next year, you earn 7% on the entire ₹10,700, not just your original investment. This might seem small initially, but over decades, the effect is dramatic. The key ingredients for compounding are returns and, crucially, time. The longer your money stays invested, the more powerful the compounding effect becomes, turning even small, regular contributions into a significant nest egg.
The Fuel: Low-Cost Index Funds and ETFs
To make compounding work effectively, you need to invest in something. This is where low-cost funds, such as index funds and exchange-traded funds (ETFs), come in. These funds are designed to be simple and efficient. Instead of trying to pick winning stocks and beat the market, they aim to match the performance of a specific market index, like the Nifty 50 or the S&P 500. By buying a single share of an index fund, you instantly own a small piece of all the companies in that index. This passive approach means the fund doesn't require a large team of analysts, making it significantly cheaper to run than an actively managed fund.
The Performance Drag: Why Costs Matter So Much
The single biggest obstacle to compounding is high fees. An investment fund’s cost is measured by its expense ratio—an annual fee taken from your investment. While a 1% or 2% fee might not sound like much, its effect over time is devastating. That's because you don't just lose the fee itself; you lose all the future growth that money would have generated. Over 20 or 30 years, a seemingly small difference in fees can consume a massive portion of your potential returns. Studies have consistently shown that low-cost funds tend to outperform their high-cost counterparts over the long run, precisely because more of your money stays invested and continues to compound for you.
The Safety Net: Diversification Reduces Risk
The old saying 'don't put all your eggs in one basket' is the essence of diversification. When you invest in a broad-market index fund, you are automatically spreading your money across hundreds or even thousands of companies in various industries and geographies. This is a powerful safety feature. If one company or even an entire sector performs poorly, the impact on your overall portfolio is cushioned by the other investments that may be doing well. This strategy isn't designed to maximize short-term gains, but to reduce volatility and minimize the risk of a catastrophic loss from a single bad investment, helping you stay invested through market ups and downs.
The Multiplier Effect: Putting It All Together
This is where the strategy becomes truly powerful. Spreading your investments across low-cost funds creates a virtuous cycle. First, diversification provides stability and reduces the kind of volatility that might cause a nervous investor to sell at the wrong time. This helps you stay in the market, which is essential for long-term compounding. Second, the low expense ratios ensure that a maximal amount of your return is reinvested each year. This larger base then generates even more returns, amplifying the snowball effect. By minimizing risk through diversification and minimizing cost drag through low fees, you create the safest and most effective environment for compounding to work its magic and build wealth steadily over time.