

Fixed Deposits: The Bedrock of Stability
Think of Fixed Deposits (FDs) as the foundation of your financial house. Their primary job isn't to make you rich overnight, but to protect your capital and provide predictable returns. When you book an FD, you lock in a specific interest rate for a set
tenure, meaning you know exactly what you'll get back and when. This assurance makes FDs an excellent tool for short-to-medium term goals, like saving for a down payment on a car or building an emergency fund. They are insulated from stock market volatility, offering peace of mind. In India, deposits up to ₹5 lakh per bank are insured by the DICGC, adding a strong layer of security. While their returns might not beat high inflation over the long run, their role is one of capital preservation and reliability, making them a non-negotiable component for risk-averse investors or for funds you simply cannot afford to lose.
Gold: The Portfolio's Insurance Policy
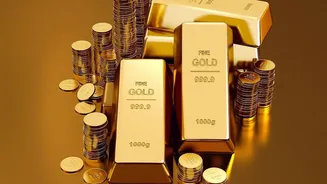
For centuries, gold has been a symbol of wealth in India, but its modern role is more strategic. Gold is your portfolio's insurance policy—a 'safe haven' asset that tends to perform well when other investments, like stocks, are struggling. It has a historically low correlation with equities, meaning its price often moves independently or even inversely to the stock market. This makes it an excellent diversification tool, helping to cushion your overall portfolio during economic downturns, geopolitical crises, or periods of high inflation. Rather than holding large amounts of physical jewellery, modern investors often prefer more efficient forms like Sovereign Gold Bonds (SGBs), which offer interest payments and tax advantages, or Gold ETFs (Exchange Traded Funds) that provide high liquidity. Financial planners often suggest allocating 5-15% of a portfolio to gold, not as a primary growth engine, but as a crucial stabiliser that protects wealth when uncertainty strikes.
Market Investments: The Engine for Growth
If FDs are the foundation and gold is the insurance, then market-linked investments like stocks and mutual funds are the engine designed to drive long-term wealth creation. These instruments give you a share in the growth of companies and the economy at large. Over long periods, equities have historically delivered returns that significantly outpace both FDs and inflation, making them essential for achieving ambitious goals like retirement or funding a child's higher education. However, this potential for high returns comes with higher risk and volatility. For those new to the market, mutual funds offer a convenient solution. They pool money from many investors and use a professional fund manager to invest in a diversified basket of stocks or bonds, instantly spreading your risk across many securities. Market investments require a long-term perspective and the discipline to stay invested through market ups and downs.
Bringing It All Together: The Power of Asset Allocation
The real magic isn't in picking one of these assets over the others, but in combining them wisely through asset allocation. This strategy involves dividing your investment capital among different asset classes to create a balanced and diversified portfolio. Your ideal mix depends on personal factors like your age, financial goals, and risk tolerance. A younger investor with a long time horizon might allocate a larger portion (e.g., 60-70%) to market investments for growth, with smaller portions in FDs for stability and gold for protection. Conversely, someone nearing retirement may have a higher allocation to FDs to preserve capital and generate regular income. The goal is to build a portfolio that can weather different economic conditions—letting your market investments drive growth, your FDs provide stability, and your gold act as a hedge. Periodically reviewing and rebalancing this mix ensures your plan stays aligned with your life goals.