



The End of the Free Lunch?
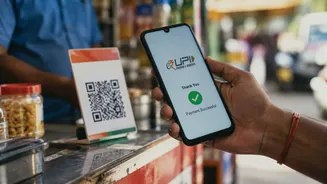
Let’s be clear: UPI is not becoming a paid service for most people. Person-to-person (P2P) transfers, like sending money to friends or family, remain completely free, regardless of the amount. The change, effective October 15, 2026, introduces a Merchant
Discount Rate (MDR) on certain person-to-merchant (P2M) payments. Specifically, a 0.4% charge will apply to merchant transactions over ₹2,000. So, if you're buying groceries for ₹500 or paying a friend ₹5,000, nothing changes for you. The new rule targets a specific slice of the digital economy: larger commercial payments.
Who Actually Pays the Fee?
This is the most crucial point: the customer does not pay this fee directly. The 0.4% MDR is levied on the merchant receiving the payment. For a transaction of ₹3,000, the merchant would incur a fee of ₹12. The government has explicitly advised banks to ensure that merchants do not pass this cost on to consumers by adding a surcharge. The fee is capped at ₹300 for any transaction of ₹75,000 or more. Certain essential sectors like railways, fuel, and insurance have a lower, flat fee of ₹5 for payments over the threshold. The rationale is that the fee, paid by the business, helps sustain the vast and expensive infrastructure that keeps UPI running smoothly.
Why Introduce Charges Now?
Until now, the UPI ecosystem has largely operated on a zero-MDR model, a policy that was instrumental in its explosive growth across India. However, running this massive real-time network—ensuring its security, speed, and reliability—costs money. Banks and payment service providers have been bearing these costs. The government previously provided subsidies, but as transaction volumes soared, this became less sustainable. Introducing a nominal MDR on high-value commercial transactions is seen as a way to create a self-sustaining revenue model for the ecosystem's participants, ensuring they can continue to invest in technology and security.
The 'Big Purchase' Dilemma
This is where the "test" comes in. While transactions over ₹2,000 are only about 4% of merchant payments by volume, they account for a much larger share of the total value. The big question is how merchants will react. While they are prohibited from adding a 'UPI charge', they could, over time, adjust prices to absorb the new cost or subtly encourage other payment methods for larger purchases, including cash. For a small business owner, a 0.4% fee on a significant sale is not trivial. Some merchants have already indicated they might pass the cost on to customers, despite the rules. This behavioural shift from both merchants and consumers will determine the true impact on India's digital payment landscape.
What Remains Unchanged
It's important to highlight what isn't affected. All P2P payments are still free. All merchant payments under ₹2,000 continue to have zero MDR. Furthermore, small merchants who receive up to ₹1 lakh per month via UPI QR codes are exempt from the new charges, protecting the smallest businesses and street vendors who have become reliant on digital payments. Essentially, for the overwhelming majority of daily transactions and for most users, the UPI experience remains exactly as it was: simple, fast, and free.