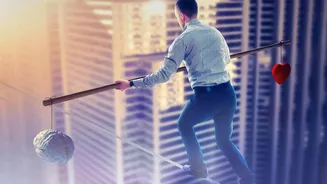





The Gig Worker’s Financial Tightrope
For millions of Indians in the gig economy, income isn't always predictable. While platforms connect workers with opportunities, the cash flow can be uneven. Payouts can fluctuate, and worse, they can be delayed. Technical glitches, platform policy changes,
or even public holidays can unexpectedly postpone the weekly or daily payments that workers rely on to cover essential expenses like fuel, rent, and daily needs. This creates significant financial stress, forcing many to dip into savings, borrow at high interest rates, or fall behind on their obligations. An unexpected delay of even a few days can throw a household's budget into chaos, highlighting the need for a reliable financial buffer.
Your Financial Safety Net: The Sweep-In Deposit
This is where a little-known but powerful banking tool called a sweep-in facility comes in. Think of it as a smart bridge between your regular savings account and a higher-earning fixed deposit (FD). It provides the high liquidity of a savings account combined with the better interest rates of an FD. Essentially, it links the two accounts. The 'sweep-in' part of the name refers to its primary function: if your savings account balance runs low and you need to make a payment, the facility automatically 'sweeps in' the exact amount of money needed from your linked FD to cover the shortfall. This prevents transaction failures and gives you access to your own money precisely when you need it, without any manual effort.
How Does It Actually Work?
Most banks in India offer this feature, sometimes called an 'Auto-Sweep' or 'Flexi Deposit'. It typically involves a two-way process. First, there's the 'sweep-out', where any amount in your savings account above a certain threshold (which you can often set) is automatically moved into a linked, higher-interest fixed deposit. This ensures your idle money works harder for you. The second, more crucial part for gig workers, is the 'sweep-in'. Imagine your savings account balance is low, but you need to pay for an urgent bike repair or an EMI. When you make the payment, the bank's system automatically pulls the required funds from your FD and credits them to your savings account to complete the transaction. This happens instantly and seamlessly in the background.
The Twin Benefits: Liquidity and Higher Returns
The most significant advantage for a gig worker is immediate liquidity. When a platform payout is late, you don't have to panic. The sweep-in facility ensures you can still access your emergency funds without the hassle of formally 'breaking' your FD and facing penalties. The funds are available through an ATM, cheque, or online transfer just like any other money in your savings account. The second major benefit is that your money doesn't just sit there. The portion of your funds that remains in the fixed deposit continues to earn a much higher interest rate than a standard savings account. This automated process helps you build a savings habit and grow your wealth, even as you maintain a safety net for emergencies.
No Penalties, Just Peace of Mind
A key feature that makes sweep-in deposits so attractive is how withdrawals are handled. Unlike a traditional FD, where breaking it prematurely often results in a penalty on the entire amount, a sweep-in works differently. Funds are typically broken in small units, sometimes as low as ₹1. The bank only moves the exact amount you need, and generally, there is no premature withdrawal penalty on the swept-in amount. The rest of your fixed deposit remains untouched and continues to earn high interest. This dynamic approach offers incredible flexibility, making it an ideal tool for managing the unpredictable income patterns inherent in gig work.
What to Ask Your Bank
Most major banks in India offer this facility, though the name might vary. When you talk to your bank, ask about their 'Auto-Sweep' or 'Sweep-in' facility. Key things to check are the threshold limit for sweeping funds out to the FD, the interest rates applicable on the FD portion, and whether there are any minimum balance requirements for the savings account to keep the facility active. Some banks also allow you to link multiple FDs to a single savings account for even greater flexibility. Understanding these details will help you choose the setup that best suits your financial situation and provides the most effective shield against income volatility.