


What Is Fixed Deposit Laddering?
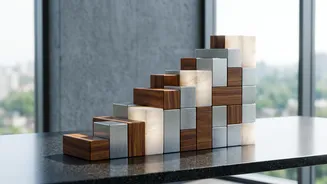
Fixed Deposit (FD) laddering is a strategy where you divide a lump-sum investment into multiple FDs with different maturity dates instead of putting the entire amount into a single FD. This creates a “ladder” of investments where a portion of your money
becomes accessible at regular intervals. For instance, instead of investing ₹5 lakh in one five-year FD, you could split it into five FDs of ₹1 lakh each, with tenures of one, two, three, four, and five years. As each FD matures, you have the choice to use the funds or reinvest them, typically into a new long-term deposit to keep the ladder going.
The Core Benefits: Interest and Liquidity
The primary advantage of laddering is that it elegantly solves the trade-off between returns and liquidity. Because longer-term FDs generally offer higher interest rates, this strategy allows a portion of your savings to benefit from these better rates. At the same time, because one FD is maturing every year (or at whatever interval you choose), you have regular access to a part of your corpus without having to break a larger deposit and incur penalties. These penalties for premature withdrawal typically range from 0.5% to 1%. Laddering also helps mitigate interest rate risk; if rates go up, you can reinvest your maturing FDs at the new, higher rates, rather than being locked into a lower rate for a long period.
How to Build Your Own FD Ladder
Building your first FD ladder is straightforward. Follow these simple steps: 1. Decide Your Total Investment: Determine the total amount you wish to invest. This strategy works best with a lump sum you don't need immediate access to. 2. Choose Your 'Rungs': Decide how many FDs you want in your ladder and their tenures. A common approach is a five-rung ladder with tenures of one, two, three, four, and five years. 3. Split the Amount: Divide your total investment equally among the rungs. For a ₹10 lakh investment on a five-rung ladder, you would create five FDs of ₹2 lakh each. 4. Invest and Stagger: Open the FDs with their different maturity dates. You now have a ladder where the first FD will mature in one year. 5. Manage and Reinvest: When the one-year FD matures, reinvest the principal and interest into a new five-year FD. The next year, do the same with the maturing two-year FD. Over time, all your FDs will become long-term deposits, but one will continue to mature every year, providing consistent liquidity.
A Practical Example in Action
Let’s take an investor with ₹5 lakh. Instead of locking it all in a 5-year FD, they create a ladder. - FD 1: ₹1 lakh for 1 year - FD 2: ₹1 lakh for 2 years - FD 3: ₹1 lakh for 3 years - FD 4: ₹1 lakh for 4 years - FD 5: ₹1 lakh for 5 years At the end of the first year, FD 1 matures. The investor can use this ₹1 lakh plus interest if needed. If not, they reinvest it into a new 5-year FD. Now, their ladder has FDs maturing in years 2, 3, 4, 5, and 6. This process is repeated annually. By the fifth year, the entire corpus is invested in high-yield 5-year FDs, but with the critical advantage of one maturing each year.
Things to Keep in Mind
While effective, laddering requires some discipline. You must track maturity dates and actively reinvest to maintain the structure. Also, consider the Deposit Insurance and Credit Guarantee Corporation (DICGC) coverage, which insures bank deposits up to ₹5 lakh per depositor, per bank. If your total investment exceeds this, consider spreading your FD ladder across different banks to ensure full coverage. Finally, remember that interest earned on FDs is taxable according to your income tax slab. If your interest income exceeds the threshold in a financial year, Tax Deducted at Source (TDS) will be applied by the bank.