


By Shashwat Chauhan and Utkarsh Hathi
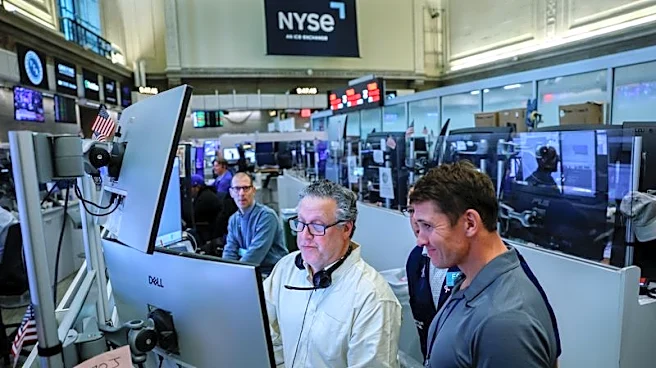
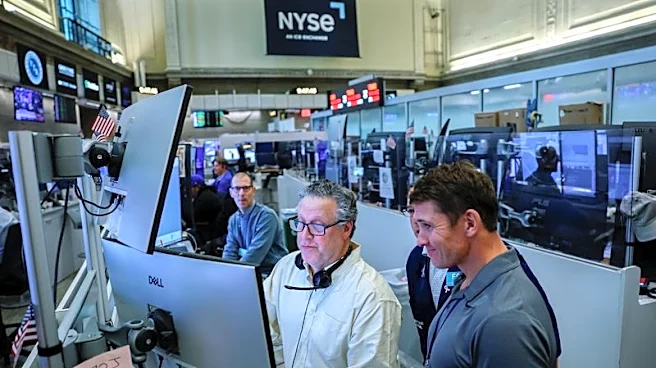
Oct 28 (Reuters) - US stocks were choppy on Wednesday as weakness in megacaps such as Tesla and Apple offset chipmaker gains sparked by SK Hynix's bumper results, while investors awaited hyperscaler earnings and the Federal Reserve's interest-rate decision later in the day.
Memory chipmaker Micron Technology jumped 4.8% to its highest in over two weeks after South Korean rival SK Hynix reported a more than sevenfold jump in quarterly profit, boosted by AI infrastructure
demand. SK Hynix's US-listed shares gained 12.2%.
The Philadelphia chips index was up 0.9%, on track to gain for the fourth straight session.
Limiting gains in main benchmarks, most megacap and growth stocks traded lower. Tesla dipped 1.3% after surging more than 9% in the last two sessions. Apple eased 0.5%, while SpaceX dropped 2.4%.
At 11:39 a.m. ET, the Dow Jones Industrial Average rose 155.89 points, or 0.30%, to 52,533.46. The S&P 500 gained 16.89 points, or 0.22%, to 7,739.58, while the Nasdaq Composite added 4.35 points, or 0.02%, to 26,482.16.
Six of the 11 major S&P 500 sectors advanced, with energy leading gains, tracking higher crude oil prices.
The Nasdaq has risen about 2% so far this week, following a bruising first half of the month, as sentiment toward AI improved after Anthropic revealed its US IPO filing on Monday.
The focus now shifts to quarterly results from hyperscalers Microsoft and Alphabet, due after markets close on Wednesday, with both companies expected to report accelerating cloud growth.
Investors will closely scrutinize their capital expenditure plans for signs that massive AI investments are generating returns, as concerns over the viability of debt-funded spending amid rising borrowing costs continue to weigh on the sector.
"We can still see that the AI demand has not paused... the number one worry for investors is not AI valuations anymore, but it's the financing through debt as debt goes through the roof in the US," said Nadia El Bilassy, senior market analyst at Equiti Group.
Alphabet shares advanced 1% following a media report that OpenAI plans to buy Google's AI chips.
Also on the day, Vertiv jumped 13.2% after the digital infrastructure provider raised full-year profit and revenue forecasts, while also topping third-quarter estimates.
Boston Scientific shed 6.6% after the medical device maker trimmed annual profit forecast.
Third-quarter earnings growth for S&P 500 companies is seen at 31.8%, revised from 31% estimated last week, according to LSEG data.
Looking ahead, the US Fed's policy announcement is due at 2 p.m. ET on Wednesday. The market consensus is widely tilted toward a pause following last month's hike, with investors more focused on remarks from Fed Chair Kevin Warsh and the policy outlook.
Market expectations, however, remain hawkish as traders see at least three 25-basis-point increases by late 2027, according to LSEG data, as persistently high inflation due to rising energy costs tied to the Middle East conflict bolster the case for tighter monetary policy.
September's Personal Consumption Expenditures report, the Fed's preferred inflation gauge, could test those bets on Thursday. Third-quarter GDP, expected to show 3.2% growth, is also due this week.
Declining issues outnumbered advancers by a 1.38-to-1 ratio on the NYSE and by 1.05-to-1 on the Nasdaq.
The S&P 500 posted 19 new 52-week highs and 11 new lows, while the Nasdaq Composite recorded 62 new highs and 141 new lows.
(Reporting by Shashwat Chauhan and Utkarsh Hathi in Bengaluru; Editing by Shilpi Majumdar)