

By Rodrigo Campos and Harry Robertson
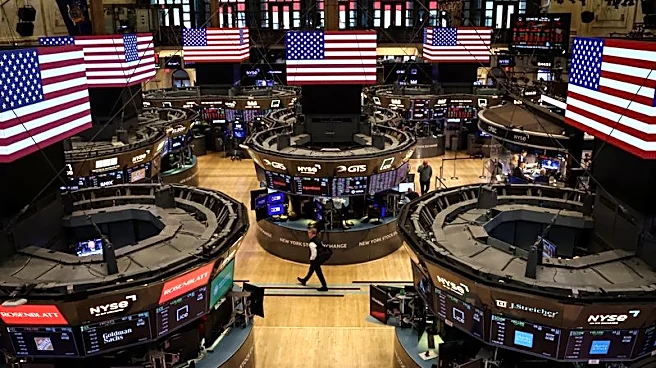
NEW YORK/LONDON, Nov 20 (Reuters) - Tumbling technology-related shares led a global stock selloff on Friday, with US traders rotating into defensive sectors and the US 10-year yield dropping by the most in a month.
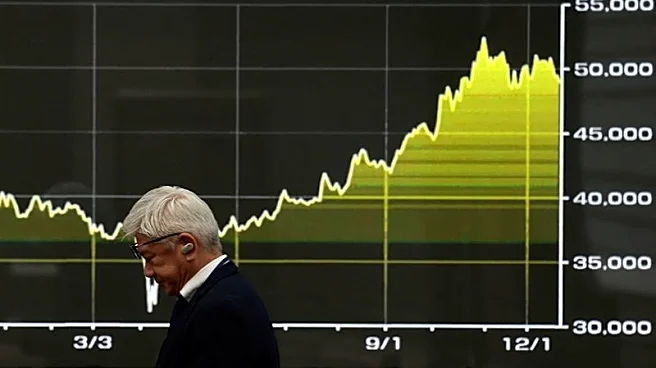
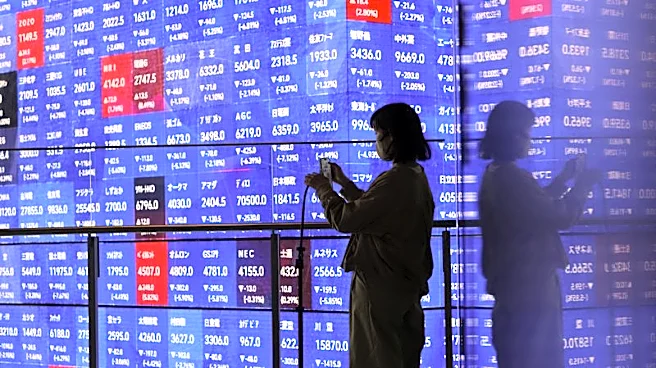
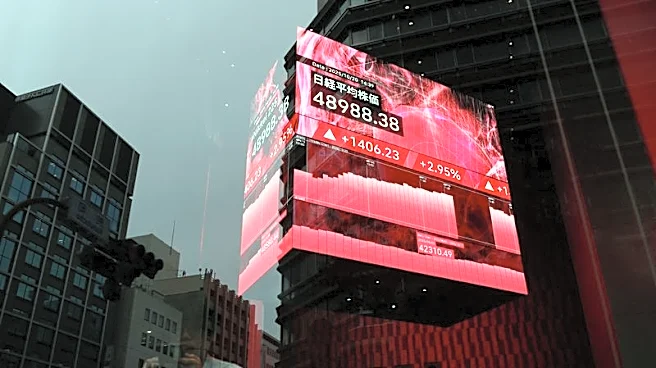
Stock benchmarks in Japan and Korea tumbled over 5% overnight to close the week, while on Wall Street chipmaker shares were down close to 6%. Taiwanese shares were down 17% for the week, their biggest weekly decline since 1990. Anthropic fell as much
as 12.5% on its first full day of trading.
Consumer staples and healthcare led sector gains on the S&P 500, which was still on track to post its largest weekly loss since March 2025.
"Markets are entering a more defensive phase," said Daniela Hathorn, senior market analyst at Capital.com.
"Strong AI demand and successful individual listings are no longer sufficient to sustain broader risk appetite when investors are questioning valuations, borrowing costs and the outlook for corporate profitability."
The Dow Jones Industrial Average rose 0.08% to 49,135.56, the S&P 500 fell 1.20% to 7,089.64 and the Nasdaq Composite fell 2.37% to 23,314.06.
MSCI's gauge of stocks across the globe fell 1.60% and the pan-European STOXX 600 index fell 1.83%. Emerging market stocks fell 3.11%.
The MSCI index of Asia-Pacific shares outside Japan tumbled 8.3% this week, its largest such drop since the COVID pandemic in March 2020.
The VIX index, linked to the cost of insurance against a drop on the S&P 500, traded at its highest since March.
As investors sought safe-haven assets, government bonds rallied.
The yield on benchmark US 10-year notes fell 10.43 basis points to 4.948% and the 30-year bond yield fell 6.39 basis points to 5.3371%. The 10-year yield is on track to post its largest daily basis point drop since October 22.
The 2-year note yield, which typically moves in step with interest rate expectations for the Federal Reserve, fell 12.57 basis points to 4.653% even as a rate hike is priced in for next month's policy meeting.
DOLLAR AND OIL DROP
The dollar index dipped after touching a 19-month high on Thursday. The dollar's recent rally has been fueled by bets on tighter monetary policy due to hotter-than-expected US inflation data.
"I think the momentum has stalled for the dollar ... but I think it's a little bit early to pick a top for the dollar," said Marc Chandler, chief market strategist at Bannockburn Capital Markets.
The dollar index fell 0.21% to 103.73, with the euro up 0.15% at $1.0982. Against the Japanese yen, the dollar weakened 0.62% to 158.7.
In commodities, crude prices fell on strong exports from the Middle East and reports of tanker disruptions in the Strait of Hormuz.
US crude fell 0.75% to $82.59 a barrel and Brent fell to $91.02 per barrel, down 1.04% on the day.
Spot gold fell 2.02% to $3,548.53 an ounce and spot silver fell 2.54% to $41.66 an ounce, both trading at their lowest since September 2025. Copper declined 2.71% to $12,186.00 a ton.
(Reporting by Rodrigo Campos, Harry Robertson, Anna Hirtenstein, Saqib Iqbal Ahmed; editing by Xevi Fontdegloria, Mark Potter and Nick Zieminski)